 Client Login
 Retirement assessment
 Book a call
 0117 990 2602


Key Takeaways
- Retirement Planning Starts with Clarity: Understand your current financial position, estimate future needs, and leverage tools like cash flow modelling to forecast your retirement journey confidently.
- Cash Flow Modelling Benefits: It helps determine how much you need to retire, identifies potential shortfalls, and offers actionable solutions like adjusting spending, saving more, or delaying retirement.
- Key Retirement Strategies: Strategies include boosting savings, optimising tax efficiency, rebalancing investments, and incorporating longevity and healthcare planning to ensure long-term financial security.
- Additional Financial Considerations: Equity release can supplement income for homeowners, and ongoing reviews of your financial plan ensure alignment with retirement goals and market conditions.
Retirement Forecaster – The Best Way to Plan for Retirement
The best retirement planning advice I give each of my clients is to get a clear picture of their finances, both now and in the future.
Most of us muddle through life, saving a bit of money here, investing a bit there. We jump from one job to another, leaving a trail of workplace pensions in our wake. Then one day, we look up and realise that we’re 55. The kids are about to leave home, and we don’t feel so young anymore.
We’ve been so busy with the here and now that we’ve forgotten to think about the future. Retirement planning felt like something we should get around to, but somehow never did. We knew its importance””it’s just never felt particularly urgent. Until now.
If you’re 50-something and starting to think about retirement, where do you start? What’s the best financial advice for someone fast approaching retirement?
Retirement Planning – How Much is Enough?
Planning for retirement can feel overwhelming. It involves estimating how much money you’ll need to sustain your lifestyle for the rest of your life.
If you’re like most people, you probably have a rough idea of how much you’ve saved for retirement””pensions, savings, and investments. You may also have a general understanding of your retirement income sources, such as buy-to-let properties, State Pensions, or final salary pensions.
But the question remains: how much is enough?
Answering this requires considering your income, expenses, taxes, investment returns, and life expectancy. This is where cash flow modelling becomes invaluable. It creates a comprehensive forecast of your finances, helping you answer “how much is enough?” with confidence.
If you want help with planning your retirement, feel free to get in touch.
Using Cash Flow Modelling to Visualise Retirement Planning
Take John and Jan. At 55, they plan to retire at 60 and aim for an annual retirement income of £50,000. Their financial position is summarised below:
- Current Income: A buy-to-let property provides £12,000 annually, and from age 68, their combined State Pensions will contribute £18,000 annually.
- Savings: £600,000 in workplace pensions and stocks and shares ISAs.
Cash flow modelling helps determine if their savings can cover the £38,000 annual shortfall before their State Pensions kick in. It factors in inflation, investment growth, tax, and life expectancy to provide a clear picture of their retirement readiness.
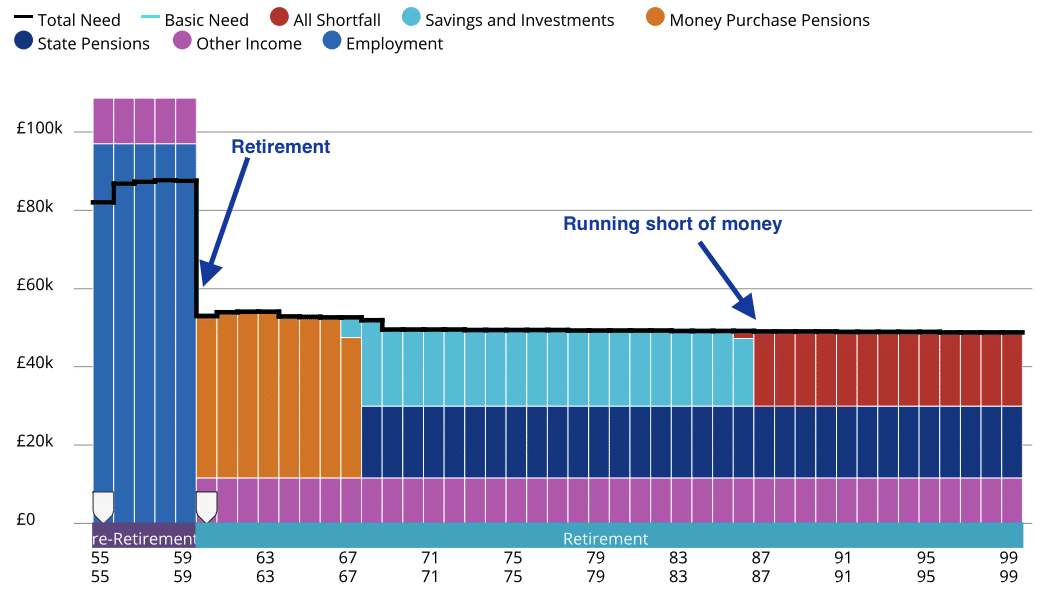
The below chart summarises their cash flow position. It shows that if they retire at 60 and spend £50,000, there is a reasonable chance that they will run short of money in their later years. The early years of retirement, before their State Pensions come into payment, required them to withdraw heavily from their savings (ISAs and pensions), leaving inadequate funds for later life.
The flip side of their cash flow position is their asset position (i.e. the capital they are spending down to fund their income shortfall). This forecasts the value of their assets over time, taking into account the withdrawals they will need to make to fund the income shortfall.
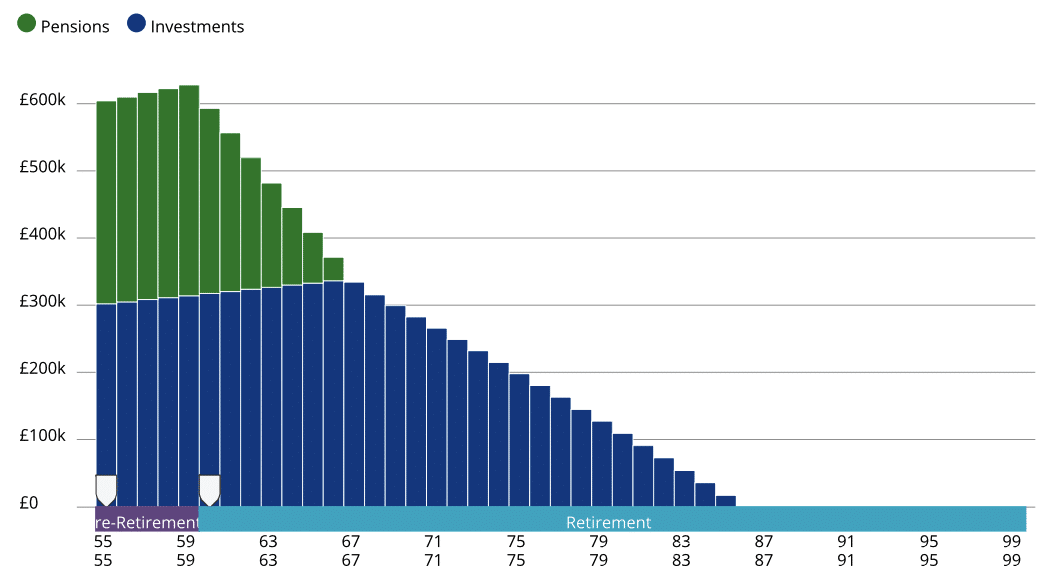
The chart shows:
- 55–60: Modest asset growth as they remain employed.
- 60–68: Significant withdrawals to cover expenses lead to asset decline.
- 68–87: Slower depletion due to State Pensions reducing reliance on savings.
- 87+: Assets are entirely depleted, leaving a shortfall in later years.
How Cash Flow Modelling Provides Retirement Clarity
With the insights from their cash flow model, John and Jan were equipped to make informed decisions about how to address their financial shortfall. The analysis highlighted several actionable options, each tailored to optimise their financial security and retirement goals:
- Postponing Retirement
Retiring at 63 instead of 60 allowed them to increase their savings while reducing the withdrawal period. The model showed that this adjustment would sustain an annual income of £50,000 throughout their retirement, eliminating the risk of running out of money in their later years. Aside from the obvious financial benefits, retiring later has several other benefits too. - Boosting Savings Contributions
By saving an additional £1,500 per month for the next five years, they could retire at 60 with a secure income of £50,000 per year. This proactive approach leveraged the compounding effect, significantly bolstering their retirement pot. - Adjusting Spending Habits
A modest reduction in annual spending to £45,000 would enable them to retire at 60 without compromising long-term financial stability. The model highlighted how small lifestyle changes could deliver substantial financial benefits. - Optimising Tax Efficiency
Strategically withdrawing funds from their pension up to their tax-free personal allowance and supplementing with ISA withdrawals reduced their overall tax liability. This strategy stretched their retirement savings further and enhanced their financial resilience. - Enhancing Investment Returns
Increasing their overall investment return by just 1% per year extended the lifespan of their savings by an additional five years. The model emphasised the importance of maintaining a well-diversified and growth-oriented investment portfolio. - Reducing Investment Costs
Lowering their annual investment costs by 0.50% kept more of their money working for them, extending the longevity of their assets by three years. Minimising fees was a straightforward yet impactful way to maximise their retirement fund.
For the first time, John and Jan gained complete clarity about their financial future. They understood their current position, where they were headed, and the specific steps they could take to secure their retirement goals. Armed with this roadmap, they felt confident in their ability to navigate retirement with peace of mind.
Best Retirement Advice: Gaining Financial Clarity
Cash flow modelling is your financial GPS, offering a clear view of your current position and future projections. It answers critical questions like, “Am I on track for a comfortable retirement?” and identifies gaps in your plan while offering actionable solutions.
Key Benefits of Cash Flow Modelling:
- Clarity on Your Financial Journey: Understand where you are today and where you’re heading.
- Customised Forecasting: Tailored insights based on your income, expenses, savings, and investments.
- Proactive Problem-Solving: Highlights shortfalls and suggests practical adjustments to stay on track.
Questions Cash Flow Modelling Can Answer:
- How much money do I need to retire?
- How much can I spend each year in retirement?
- What level of risk is appropriate for my investments?
Cash flow modelling provides a structured, data-driven approach to retirement planning. With a clear financial roadmap, you can make informed decisions and approach retirement with confidence.
Health and Longevity Planning
As life expectancy continues to increase, planning for a longer retirement has never been more critical. When determining how much is enough, it’s essential to factor in the possibility of living into your 90s or beyond. A longer retirement period requires more savings and strategic withdrawals to ensure your money lasts.
- Consider healthcare costs, especially as medical needs typically increase with age.
- Account for potential long-term care needs and explore financial options like long-term care insurance.
- Build a buffer into your retirement plan for unexpected health-related expenses.
Including longevity considerations in your retirement forecast ensures you remain financially secure throughout your lifetime.
Housing and Equity Release
For many retirees, housing is both a significant asset and a potential source of income. If you’re a homeowner, equity release can provide an additional income stream to support your retirement goals.
- What is equity release? Equity release allows you to access the value tied up in your home, either as a lump sum or a regular income, without having to sell your property.
- Who is it suitable for? It’s a useful option for retirees who own their home outright or have minimal mortgage debt and want to supplement their retirement income.
- Things to consider: While equity release can provide financial flexibility, it reduces the value of your estate and may impact inheritance plans. Consulting a financial adviser ensures you understand the implications.
Exploring equity release as part of your retirement strategy can enhance financial freedom while maintaining your current lifestyle.
Investment Strategy Adjustments Near Retirement
As you approach retirement, the way your pension is invested should reflect your changing priorities. Protecting your savings becomes just as important as growing them.
- Rebalancing Your Portfolio: Transitioning to a lower-risk investment strategy can help preserve the value of your pension. Consider shifting some funds into bonds, cash, or other stable assets to reduce exposure to market volatility.
- Diversification: Even as you reduce risk, maintaining a well-diversified portfolio ensures your investments are resilient across different market conditions.
- Ongoing Reviews: Regularly reviewing your pension investments with a financial adviser ensures your strategy aligns with your retirement timeline and risk tolerance.
Adjusting your investment strategy ensures your savings are well-positioned to support your retirement income needs while safeguarding against unexpected market downturns.
The Bottom Line: Take Control of Your Retirement
Retirement is one of life’s most significant transitions””something you’ll only do once and something you’ll want to get right. With so much at stake, careful and informed planning is essential. Cash flow modelling offers a powerful, detailed view of your financial landscape, enabling you to make smarter, more confident decisions about your future.
By leveraging the insights from cash flow modelling, you can:
- Determine whether you’re on track to meet your retirement goals.
- Identify and address potential shortfalls before they become challenges.
- Make informed adjustments to your spending, savings, and investment strategies.
Take the guesswork out of retirement planning and replace it with clarity and confidence.
If you’re ready to take the next step, book your Retirement Consultation today. Our team of retirement planning experts will work closely with you to explore your options and develop a strategy tailored to your unique circumstances. Let’s ensure your retirement is everything you’ve worked so hard for.
Financial Advisor Bristol and Pension Advisor Clifton
Frazer James Financial Advisers is an Independent Financial Advisor Bristol.
About us: We, Frazer James Financial Advisers, are financial advisors and retirement planners in Bristol. As an independent financial adviser, we’re able to provide independent and unbiased financial advice. We provide independent financial advice, pension advice, investment advice, inheritance tax planning and insurance advice.
If you would like to speak to a Financial Advisor, we offer an Initial Financial Consultation without cost or commitment. Meetings are held either at our offices, by video or by telephone. Our telephone number is 0117 990 2602.
Frazer James Financial Advisers is located at Square Works, 17 – 18 Berkeley Square, Bristol, BS8 1HB.
This article provides information about investing, but not personal advice. If you’re not sure which investments are right for you, please request advice.
Remember that investments can go up and down in value, you may get back less than you put in.