 Client Login
 Retirement assessment
 Book a call
 0117 990 2602



If you receive the full new State Pension in 2026/27, you can earn just £22 of other taxable income before income tax starts. That is not a typo. The full new State Pension is £241.30 a week, which adds up to £12,548 a year. The personal allowance, the amount you can earn before paying income tax, is £12,570. The gap between them is £22.
Most people assume retirement brings a comfortable distance from the tax threshold. The numbers tell a different story. This article will show you exactly how that £22 headroom works, how HMRC collects tax on income that arrives without any deducted at source, and how the savings rules can shelter thousands of pounds of interest if you understand how to stack them correctly.
You’ll learn three things. First, how the State Pension interacts with the Personal Allowance in 2026/27. Second, why the State Pension can feel tax-free even though it isn’t. Third, how the savings starting rate can reduce tax on a modest retirement income. If you are approaching retirement and want to understand how it all fits together, our retirement planning service is a good place to start.
The £22 question: how close is the State Pension to the tax threshold?
The personal allowance for 2026/27 is £12,570. It has been frozen at this level since 2021 and is set to remain frozen until at least 2028. The full new State Pension, after the 4.8% triple lock rise, is £12,548 a year. That leaves £22 of your personal allowance unused.
This matters because the triple lock guarantees the State Pension rises each year by the highest of inflation, average earnings growth, or 2.5%. However, the personal allowance, which is the amount you can receive tax-free, is frozen. The math is simple: if the State Pension rises by at least 2.5% next April, it will exceed £12,570. As a result, the State Pension alone will push a pensioner into income tax for the first time. That is not a prediction; it is the direction the numbers are already pointing.
The practical consequence is simple. If you receive the full new State Pension and have other taxable income, you are likely to pay tax. That could include a private pension, part-time earnings or rental income.
The question is not whether you pay tax. It is how much you pay, and whether that amount is correct.
Tax rules, allowances and legislation can change. The figures above apply to 2026/27 for England, Wales and Northern Ireland. Scotland has different income tax bands, so if you are a Scottish taxpayer, your position may differ.
Which income counts towards your tax threshold in retirement?
The personal allowance applies to your total taxable income, not to any single source. Several types of income count towards it.
The State Pension (both the basic and new State Pension)
Private and workplace pension income, including annuity payments
Employment or self-employment earnings
Rental income from property
Savings interest (above the relevant allowances, more on this below)
Dividends above the £500 dividend allowance
Certain taxable benefits, such as Carer’s Allowance
Some income does not count. The 25% tax-free element of a pension lump sum is not taxable. ISA income is not taxable. The first £500 of dividends is covered by the dividend allowance. And savings interest has its own set of rules that can be genuinely generous for pensioners on modest incomes.
One thing worth understanding clearly: there is no separate, higher personal allowance for pensioners. The age-related allowance that existed before 2016 no longer applies. Everyone gets the same £12,570, regardless of age.
Why your State Pension is taxable, even though no tax is deducted
The Department for Work and Pensions pays the State Pension ‘gross’. This means that no tax is deducted before it reaches your bank account. This is why many people genuinely believe their State Pension is tax-free. It is not. It is taxable income. HMRC simply collects the tax in a different way.
If you also receive a private or workplace pension through PAYE (Pay As You Earn), HMRC adjusts your tax code on that pension to collect the tax owed on your State Pension. Your private pension provider deducts more tax than it otherwise would, effectively collecting the liability on HMRC’s behalf. The Low Incomes Tax Reform Group explains this mechanism clearly in their guide to how tax is collected on the State Pension.
If you have no PAYE income, no private pension, and no employment, HMRC may issue a Simple Assessment. This is a tax calculation sent directly to you, showing what you owe and how to pay it. You do not need to complete a full Self Assessment tax return in most cases, but you do need to pay the bill.
The practical risk here is underpayment. If your tax code is wrong, or if HMRC does not have accurate information about all your income sources, you may build up a tax debt without realising it. If you think your code looks unusual, it is worth checking with HMRC or speaking to a financial adviser.
How the savings interest rules can work in your favour
This is the area where most people leave money on the table, not through any fault of their own, but because the rules are genuinely complicated and almost nobody explains them clearly.
There are three layers of allowance that can apply to savings interest, and they stack on top of each other for pensioners on modest incomes.
Layer one: the personal allowance. If your total income is below £12,570, savings interest uses up whatever personal allowance remains. For a pensioner on the full new State Pension, that is just £22.
Layer two: the starting rate for savings. If your non-savings income, such as State Pension, private pension or employment income, is below £17,570, you may qualify for a 0% tax rate on up to £5,000 of savings interest. The band reduces by £1 for every £1 of non-savings income above the £12,570 Personal Allowance. For example, the full new State Pension is £12,548, leaving £22 of Personal Allowance unused. You could therefore receive £22 of interest within your Personal Allowance, plus another £5,000 at the 0% starting rate: £5,022 of savings interest without paying tax.
Layer three: the Personal Savings Allowance. Basic rate taxpayers can receive a further £1,000 of savings interest tax-free through the Personal Savings Allowance. This falls to £500 for higher rate taxpayers and £0 for additional rate taxpayers.
Stack the allowances correctly and someone whose only other income is the full new State Pension could receive around £6,022 of savings interest without paying tax: £22 within their remaining Personal Allowance, £5,000 at the 0% starting rate for savings, and £1,000 within their Personal Savings Allowance.
Consider Neil. He receives the full new State Pension and has £80,000 in cash savings, with no other income. He could earn around £6,022 of interest before paying tax on it. However, this tax-free capacity falls quickly as private pension or other non-savings income rises above the Personal Allowance, with the £5,000 starting-rate band disappearing completely once non-savings income reaches £17,570.
For married couples, there may be further opportunities. The Marriage Allowance allows an eligible lower-earning spouse to transfer part of their Personal Allowance to their partner. We cover this in our article on four ways marriage can reduce your tax bill.
A worked example: tax due for three different retirement incomes in 2026/27
The table below shows how income tax works across three illustrative scenarios for 2026/27. These are examples only and do not account for savings interest, dividends or individual circumstances. Tax rules may change.
Scenario | State Pension | Other income | Total income | Personal allowance used | Taxable income | Tax due (20%) |
|---|---|---|---|---|---|---|
State Pension only | £12,548 | £0 | £12,548 | £12,548 of £12,570 | £0 | £0 |
State Pension + £6,000 private pension | £12,548 | £6,000 | £18,548 | £12,570 (fully used) | £5,978 | £1,195.60 |
State Pension + £20,000 drawdown | £12,548 | £20,000 | £32,548 | £12,570 (fully used) | £19,978 | £3,995.60 |
The third scenario assumes £20,000 of fully taxable pension income. Any tax-free cash withdrawn from the pension is separate and is not included in the figures above. It does not assume any of the withdrawal is tax-free. For more on how pension withdrawals become taxable income, our article on understanding crystallised pensions explains the mechanics in full.
What happens when your income crosses into the higher rate band?
For most people in England, Wales and Northern Ireland, income above £50,270 is taxed at 40%, while income above £125,140 is taxed at 45%. Scotland has different income tax bands.
There is also an important trap for those earning between £100,000 and £125,140. Your Personal Allowance reduces by £1 for every £2 of income above £100,000 and disappears completely at £125,140. This creates an effective marginal Income Tax rate of 60% on income within this range, making the timing of large pension withdrawals particularly important.
Your Personal Savings Allowance can also fall as your income rises. Basic rate taxpayers receive £1,000, higher rate taxpayers £500, and additional rate taxpayers receive no allowance. So if your income pushes you into the higher-rate band, the amount of savings interest you can receive tax-free may fall, too.
Does drawdown timing affect how much tax you pay?
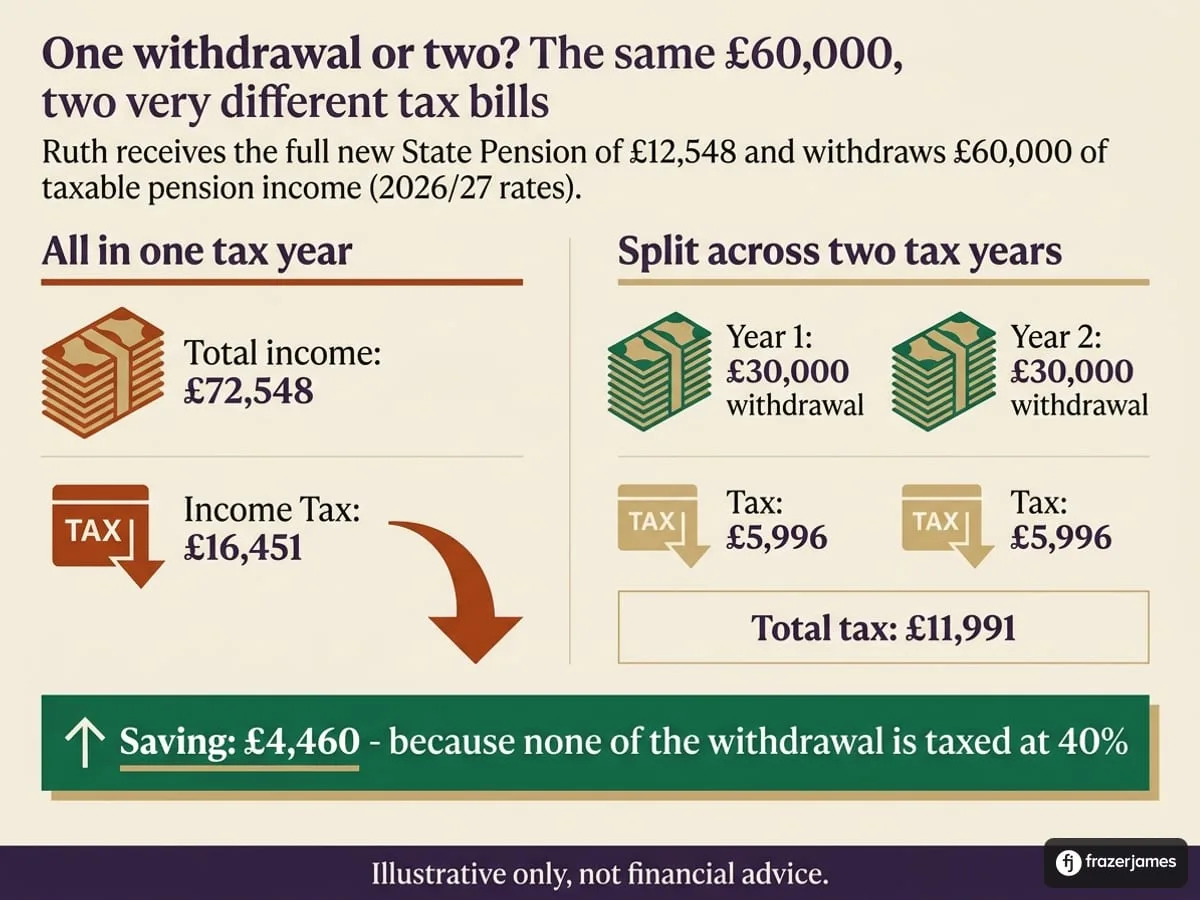
Yes. Pension withdrawals are generally taxable income in the year you take them. A large withdrawal can push some of your income into a higher tax band, reduce your Personal Allowance or reduce your Personal Savings Allowance. Spreading the same withdrawal across two tax years can therefore produce a much lower tax bill.
Consider Ruth, who receives the full new State Pension and wants to withdraw £60,000 of taxable income from her pension. If she takes it all in one tax year, her total income is £72,548 and her Income Tax bill is around £16,451. If she instead takes £30,000 in each of two tax years, her tax bill is around £5,996 per year, or £11,991 in total. That’s a saving of around £4,460, largely because none of the pension withdrawals are taxed at 40%.
What to do if you think you are paying too much, or too little, tax
If your only income is the State Pension and it falls below the personal allowance, you should not be paying income tax. If you are, contact HMRC to check your tax code.
If you have multiple income sources, such as State Pension, a private pension, savings interest, and rental income, the interaction between them can produce unexpected results. An incorrect tax code, a missing allowance, or a poorly timed withdrawal can all lead to overpayment or underpayment.
HMRC’s guidance on tax when you get a pension is a useful starting point. For anything more complex, speaking to a Certified Financial Planner is worth considering.
At Frazer James, we work with clients who are approaching or recently into retirement and want to understand exactly where they stand. One of our clients described how his focus shifted when he started working with us: “I had been fixated on reaching a particular pension number, without really knowing whether that number was enough, too much, or what it would actually mean for our retirement. James asked my wife and me what we actually wanted our retirement to look like. He then showed us how our existing position compared with those goals and laid out a clear, structured plan.” That kind of clarity across pensions, tax, and income is what good financial planning looks like in practice.
If you are thinking about how your retirement income will be taxed, and whether your current plan accounts for the interactions between State Pension, private pension and savings, our planning your retirement page sets out how we approach this with clients. You can also book a free consultation to talk through your specific situation with no obligation.
Frequently Asked Questions
How much can I earn on top of State Pension before tax?
In 2026/27, the full new State Pension is around £12,548 a year and the Personal Allowance is £12,570. That leaves just £22 of unused Personal Allowance. So, if you receive the full new State Pension, only £22 of additional taxable income, such as private pension or employment income, can usually be received before Income Tax becomes due. Savings interest is treated differently because the starting rate for savings and Personal Savings Allowance may apply.
How much savings can a pensioner have in the bank in the UK before tax?
There is no limit on how much you can hold in savings. What matters is the interest those savings generate. In 2026/27, someone whose only other income is the full new State Pension could potentially receive around £6,022 of savings interest without paying tax: £22 within their remaining Personal Allowance, £5,000 at the 0% starting rate for savings and £1,000 within their Personal Savings Allowance. The £5,000 starting-rate band reduces as non-savings income rises above £12,570 and disappears completely at £17,570.
Do I need to complete a tax return if I am retired?
Not necessarily. Many pensioners do not need to complete a Self Assessment tax return. Tax on private pensions can usually be collected through PAYE, while HMRC may use Simple Assessment for tax that cannot be collected this way. However, certain income or circumstances can require you to file a tax return. You can use HMRC’s online checker if you are unsure.
What is considered a low income for a pensioner?
The standard Personal Allowance is £12,570 in 2026/27. The full new State Pension is around £12,548, just £22 below this threshold. Someone receiving the full new State Pension therefore has very little Personal Allowance remaining for other taxable pension or employment income. Different rules apply to savings income, while benefits such as Pension Credit have separate eligibility and means-testing rules.