 Client Login
 Retirement assessment
 Book a call
 0117 990 2602


Modified on: August 2026
Self-employed contractors income protection guide
A Complete Guide to Income Protection Insurance for Contractors
As a self-employed contractor, your income is your lifeline. But what happens if illness or injury prevents you from working? Income protection insurance for contractors provides financial security by replacing a portion of your income if you’re unable to work. It’s a tailored solution designed to offer contractors peace of mind, even during challenging times.
In this guide, we’ll explore the importance of contractor protection, how income protection works, and the key considerations for choosing the right policy.
What is Income Protection for Contractors?
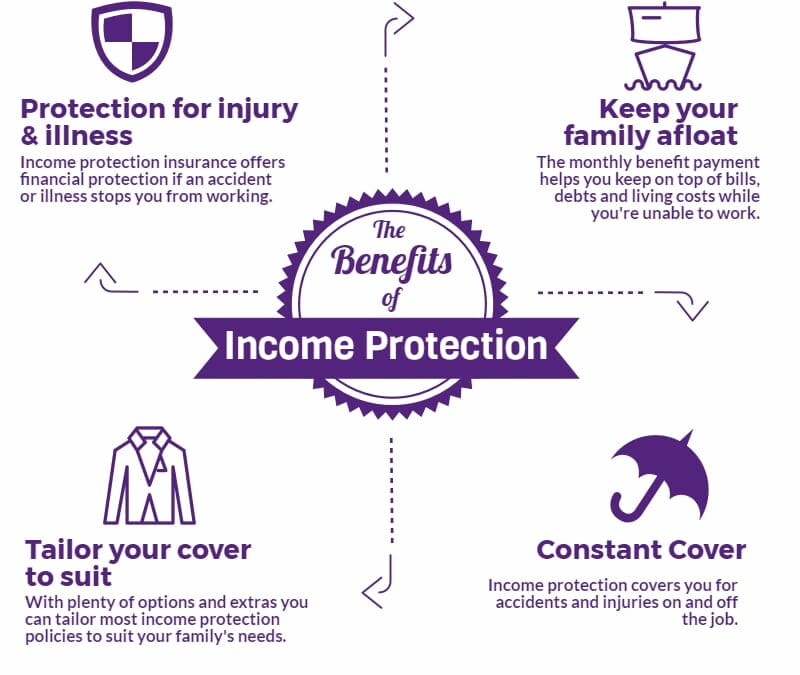
Income protection insurance for contractors is a policy that provides a replacement income if you’re unable to work due to illness or injury. It ensures you can maintain financial stability by covering up to 70% of your income, including salary, dividends, and bonuses.
Two types of income protection policies are available:
- Long-term cover: Pays out until you retire, return to work, or pass away.
- Short-term cover: Offers protection for up to one or two years, often at a lower premium.
This form of contractor protection, also known as contractor sickness insurance, was formerly referred to as permanent health insurance.
Why Should Self-Employed Contractors Consider Income Protection?
Unlike employees, who may benefit from employer-provided sickness cover, contractors are solely responsible for their financial safety net. If you’re unable to work due to accident, illness, or injury, your income could stop overnight. Income protection insurance for contractors ensures you won’t face financial hardship in such situations.
Key Benefits of Contractor Protection
- Financial Security: Provides a tax-free replacement income, ensuring you are financially secure if you’re unable to work.
- Flexible Cover: Tailored policies let you choose how much income to protect and how long you’re covered.
- Independence from Government Support: Employment and Support Allowance (ESA) offers limited help, with payouts between £57.90 and £111.65 per week””rarely enough to cover essential bills.
Example: A contractor earning £50,000 annually could receive up to £35,000 per year in tax-free benefits with the right income protection policy.
Do Contractors Need Income Protection?
If your income is essential to cover bills, mortgage payments, or family expenses, then income protection insurance for contractors is crucial. Ask yourself:
- How long could I manage without an income?
- Do I have dependents relying on my earnings?
While maintaining a few months’ worth of expenses in savings is sensible, prolonged illnesses or injuries could deplete your reserves quickly. Without a robust contractor protection plan, financial strain could jeopardise your business and personal well-being.
What Does Contractor Income Protection Cover?
Income protection policies cover accidents, illnesses, or injuries that prevent you from working. You can insure up to 70% of your income, including:
- Salary
- Dividends
- Bonuses (if applicable)
Exclusions:
- Self-inflicted injuries.
- Conditions resulting from alcohol or drug misuse.
- Redundancy or unemployment unrelated to health issues.
Always review the key features of a policy to understand the terms fully.
Additional Options for Income Protection
Customising your policy ensures it meets your unique needs. Here are the main features to consider:
1. Waiting Period (Deferred Period)
The waiting period is the time between when you stop working and when the policy begins to pay out. Options range from 1 week to 12 months. Longer deferred periods reduce premiums but require you to cover initial expenses independently.
2. Occupation Type
Choose from three levels of cover:
- Any occupation: Pays out only if you cannot perform any job. (Cheapest but least comprehensive.)
- Suited occupation: Covers jobs suited to your skills but may not cover your exact role.
- Own occupation: Provides payouts if you’re unable to perform your specific role. (Most comprehensive.)
3. Increasing Cover
The type of cover you select will either be:
- Level cover: Fixed payouts.
- Inflation-linked cover: Increases payouts annually to keep pace with rising costs.
4. Waiver of Premium
This feature suspends premium payments while you’re claiming benefits, ensuring your policy remains active without added financial pressure.
How Much Income Protection Cover Do Contractors Need?
To determine the right level of cover, consider your monthly expenses:
- Fixed costs: Rent/mortgage, utilities, groceries.
- Savings: Ensure you continue setting aside money for retirement or emergencies.
Example: If your monthly income is £3,000 and expenses are £2,000, aim for a policy covering 66% of your income (£2,000/month).
How Much Does Income Protection Insurance for Contractors Cost?
The cost depends on several factors:
- Age: Premiums increase with age.
- Health: Pre-existing conditions may affect eligibility or premiums.
- Occupation type: Higher-risk jobs lead to higher premiums.
- Deferred period: Longer waiting times reduce costs.
- Coverage amount: Policies covering higher incomes are more expensive.
Example: A healthy 30-year-old contractor working in an administrative role might pay £20–£30 per month for basic cover.
What is the Best Income Protection Policy for Contractors?
The best policy will depend on your specific needs, such as:
- How much income you need to replace.
- How long you can wait before receiving payouts.
- The duration of coverage you require.
While there are income protection calculators available, they don’t take into account all of your personal circumstances. Consulting an independent financial adviser ensures your policy is tailored to your personal and professional circumstances.
Other Types of Contractor Protection
While income protection insurance for contractors is vital, other policies can further safeguard your finances:
- Life Insurance: Provides a lump sum to your family in the event of your death.
- Critical Illness Cover: Pays out a lump sum if diagnosed with a severe illness, such as cancer or heart disease.
- Private Medical Insurance: Covers private healthcare, helping you recover and return to work faster.
- Keyman Insurance: Protects your business by providing a payout if a key individual (including yourself) can no longer work.
How to Get Help with Income Protection
Finding the right policy can be complex. At Frazer James, we specialise in contractor protection, helping self-employed professionals secure their income and financial future.
During our initial consultation, we will:
- Review your existing coverage.
- Assess your income protection needs.
- Recommend tailored solutions.
Ready to get started? Go ahead and book an initial consultation.
Financial Advisor Bristol and Pension Advisor Clifton
Frazer James Financial Advisers is an Independent Financial Advisor Bristol, Clifton.
About us: Frazer James Financial Advisers is a financial advisor, based in Clifton, Bristol. As an independent financial adviser, we’re able to provide independent and unbiased financial advice. We provide independent financial advice, pension advice, investment advice, inheritance tax planning and insurance advice.
If you would like to speak to a Financial Advisor, we offer an Initial Financial Consultation without cost or commitment. Meetings are held either at our offices, by video or by telephone. Our telephone number is 0117 990 2602.
Frazer James Financial Advisers is located at Square Works, 17 – 18 Berkeley Square, Bristol, BS8 1HB.
This article provides information about investing, but not personal advice. If you’re not sure which investments are right for you, please request advice.
Remember that investments can go up and down in value, you may get back less than you put in.
About The Author

FAQs
How does sickness insurance differ from income protection?

How much does sickness insurance typically pay out?
How long do sickness insurance payouts last?
What are the eligibility criteria for sickness insurance?
Can I get sickness insurance if I have pre-existing health conditions?
Is sickness insurance tax-deductible for self-employed individuals?
What is the difference between short-term and long-term income protection for contractors?
How do deferred periods impact contractor income protection policies?
Can contractors choose how much income protection cover they need?
Does income protection cover redundancy for contractors?
Why should contractors opt for 'own occupation' income protection?
How does income protection work for self-employed contractors with variable income?
Related news


Get in touch
Schedule a free consultation with one of our financial advisers, or give us call.
0117 990 2602