 Client Login
 Retirement assessment
 Book a call
 0117 990 2602


Modified on: September 2026
How to Retire Early in the UK: A Guide for Successful Professionals

How to Retire Early in the UK: A Guide for Successful Professionals
What if the biggest obstacle to retiring early isn’t how much money you have – but not knowing exactly how much is enough? Most successful professionals we speak to aren’t short of assets. They have pension pots, ISAs, investments, property, and in many cases a business with real value. What they lack is a structured, tax-efficient plan that turns those assets into a reliable, lasting income – one that works from the day they stop working, not just from the day the State Pension kicks in.
If you’ve worked hard, built real wealth, and found yourself wondering whether you could actually stop – or at least choose when and how you work – this guide will show you exactly what early retirement requires in the UK, walk you through the key financial milestones and pension rules you must plan around, and reveal the three planning decisions that most high earners get wrong when they try to retire before 60.
We’ll cover how to calculate a realistic income target, how to navigate the pension access age change arriving in April 2028, and – critically – how to sequence withdrawals across your ISAs, SIPPs, and other assets in a way that minimises tax and maximises longevity. This is the part no mass-market guide addresses. It’s also the part that makes the biggest difference.
If you’re already thinking seriously about your timeline, our retirement planning for professionals page sets out how we approach this with clients at every stage.
What does retiring early actually mean in the UK – and is it the right goal for you?
In the UK, “early retirement” typically means leaving full-time work before the State Pension age, which is currently 66 for both men and women and is scheduled to rise to 67 between 2026 and 2028. But for most of the professionals and business owners we work with at Frazer James, early retirement means something more specific: achieving financial independence before they’re forced to stop, so that work becomes a choice rather than a necessity.
That distinction matters. Some clients want to stop entirely at 55. Others want to step back to two days a week at 58. Others want to sell their business at 60 and never think about money again. The financial planning required for each of these scenarios is different – and the tax implications are very different indeed.
Early retirement is not simply a savings challenge. For high earners with multiple asset types, it is a sequencing and structuring challenge. The question isn’t just “do I have enough?” It’s “how do I draw this down in the right order, at the right time, without handing a disproportionate share to HMRC?”
Is it possible to retire early in the UK without a large pension pot?
Yes, but the strategy changes significantly. If your wealth is concentrated in property, a business, or a General Investment Account rather than a pension, you need a plan that accounts for the different tax treatment of each asset. ISA withdrawals are tax-free. Pension drawdown is taxed as income. Property rental income is taxed at your marginal rate. A business sale may trigger Capital Gains Tax, though Business Asset Disposal Relief can reduce this substantially. The mix of assets you hold determines the sequencing strategy – and getting it wrong can cost tens of thousands of pounds in unnecessary tax.
The number you really need: how to calculate your early retirement income target
Before any sequencing strategy makes sense, you need a clear income target. This sounds obvious, but it’s the step most people skip – or get wrong. One client, who came to us having managed his own pension with a focus on high-risk technology investments, described exactly this problem: “I had been fixated on reaching a particular pension number – without really knowing whether that number was enough, too much, or what it would actually mean for our retirement.”
The first step is to separate your spending into two categories: essential costs (housing, food, utilities, healthcare, insurance) and discretionary spending (travel, hobbies, gifts, dining). Both need to be inflation-adjusted. A retirement starting at 55 could last 35 years or more. At 3% annual inflation, your living costs will roughly double over that period. Planning for what you spend today is not planning for retirement – it’s planning for the first five years of it.
A widely referenced starting point is the 4% withdrawal rule, which suggests that withdrawing 4% of your portfolio annually gives a high probability of the money lasting 30 years. On that basis, a £50,000 annual income target requires a portfolio of approximately £1.25 million. But this rule was developed using US market data and doesn’t account for the UK tax system, the State Pension income that will eventually arrive, or the specific asset mix of a high-earning professional. It’s a useful anchor, not a plan.
What actually works is cashflow forecasting: modelling your income, expenditure, tax position, and asset drawdown year by year, adjusting for the State Pension arriving at 67, for inflation, and for different market scenarios. This is the foundation of the work we do with clients at Frazer James, and it’s what transforms a vague aspiration into a specific, confident decision.
How much money do I need to retire early in the UK?
There is no single answer, because the number depends on your target income, your expected retirement length, your asset mix, and your tax position. As a rough guide, someone targeting £40,000 per year in today’s money, retiring at 55, and expecting to live to 85 would need a portfolio of approximately £800,000 to £1.2 million – depending on investment returns, inflation, and when the State Pension begins supplementing their income. The State Pension (currently £12,548 per year for the full new State Pension in 2026/27) reduces the private income you need to generate from age 66 onwards, which meaningfully reduces the total pot required. A Chartered Financial Planner can model this precisely for your circumstances, accounting for your specific asset types and tax position.
Pension access rules: what the minimum pension age means for your early retirement timeline
This is the rule that catches people out most often. You cannot access your private pension – whether a workplace pension, a SIPP, or a personal pension – before the minimum pension access age. That age is currently 55. But from 6 April 2028, it rises to 57.
The practical implication: if you are currently 53 or 54 and planning to retire at 55, you need to act before April 2028 or accept that your pension will be locked until you are 57. If you are 56 and planning to retire this year, you can access your pension now under the current rules. The window is closing, and the decisions you make in the next 18 months could significantly affect your options.
There are limited exceptions. Serious ill health can allow earlier access. Some older pension schemes have a “protected pension age” that preserves access at 55 even after the rule change – but this protection can be lost if you transfer the pension to a new provider without careful planning. This is exactly the kind of detail that gets missed without specialist advice.
According to GOV.UK’s guidance on early retirement and pensions, the State Pension cannot be claimed before you reach State Pension age regardless of when you stop working. Your National Insurance record determines the amount you receive, and gaps in contributions during early retirement years can reduce your entitlement. Paying voluntary National Insurance contributions during retirement to protect your record is often worth considering.
What is the earliest age I can access my pension in the UK?
Currently, the minimum pension access age is 55. From 6 April 2028, this rises to 57 for most people. The only exceptions are serious ill health, certain protected pension ages under older scheme rules, and specific public sector schemes. If you are planning to retire before 57 and your primary asset is a pension, you need a bridging strategy to fund the gap – or you need to act before the April 2028 deadline. This is one of the most time-sensitive planning decisions facing anyone currently in their mid-50s.
Bridging the gap: how to fund the years between early retirement and your State Pension
This is the planning challenge that separates a well-structured early retirement from a financially stressful one. If you retire at 55, you face up to 11 years before the State Pension begins at 66. If the minimum pension access age rises to 57 and you retire before that, you may also face a gap before your pension is accessible. You need income from somewhere.
The most common bridging sources are ISAs, General Investment Accounts (GIAs), rental income from property, and – for business owners – proceeds from a business sale or retained profits drawn down tax-efficiently before exit. Each has a different tax profile, and the order in which you draw from them matters enormously.
One couple, clients who came to us wanting to explore early retirement, faced exactly this challenge. They had pension wealth they couldn’t yet access, ISA savings, and a property portfolio generating rental income. By modelling the most tax-efficient sequence for drawing down each source, we helped them understand that early retirement was not only possible but achievable sooner than they had imagined. They are now retired and sailing the Mediterranean – a goal that had seemed out of reach until they had a clear, structured plan.
For those with a gap before pension access, ISA withdrawals are the cleanest bridging tool: no income tax, no impact on your personal allowance, and no interaction with other income sources. Drawing from ISAs first, before touching your pension, preserves the pension’s tax-free growth for longer and keeps your taxable income lower in the early retirement years.
The MoneyHelper guidance on pensions and retirement provides a useful overview of the options available, though it does not address the sequencing question in depth for those with multiple asset types.
How do I bridge the income gap between early retirement and State Pension age?
The most tax-efficient approach for most high earners is to draw from ISAs first, then from pension drawdown, then from other taxable sources – adjusting the mix each year to stay within lower tax bands. If you have rental income or dividend income running alongside, the sequencing becomes more complex: you need to account for how each source interacts with your personal allowance, the basic rate band, and the higher rate threshold. A cashflow model built by a Chartered Financial Planner will show you the optimal sequence year by year, not just in aggregate.
Tax-efficient drawdown: sequencing your ISAs, SIPPs, and investments in the right order
This is the section that most early retirement guides skip entirely. It is also the section that makes the biggest financial difference for high earners.
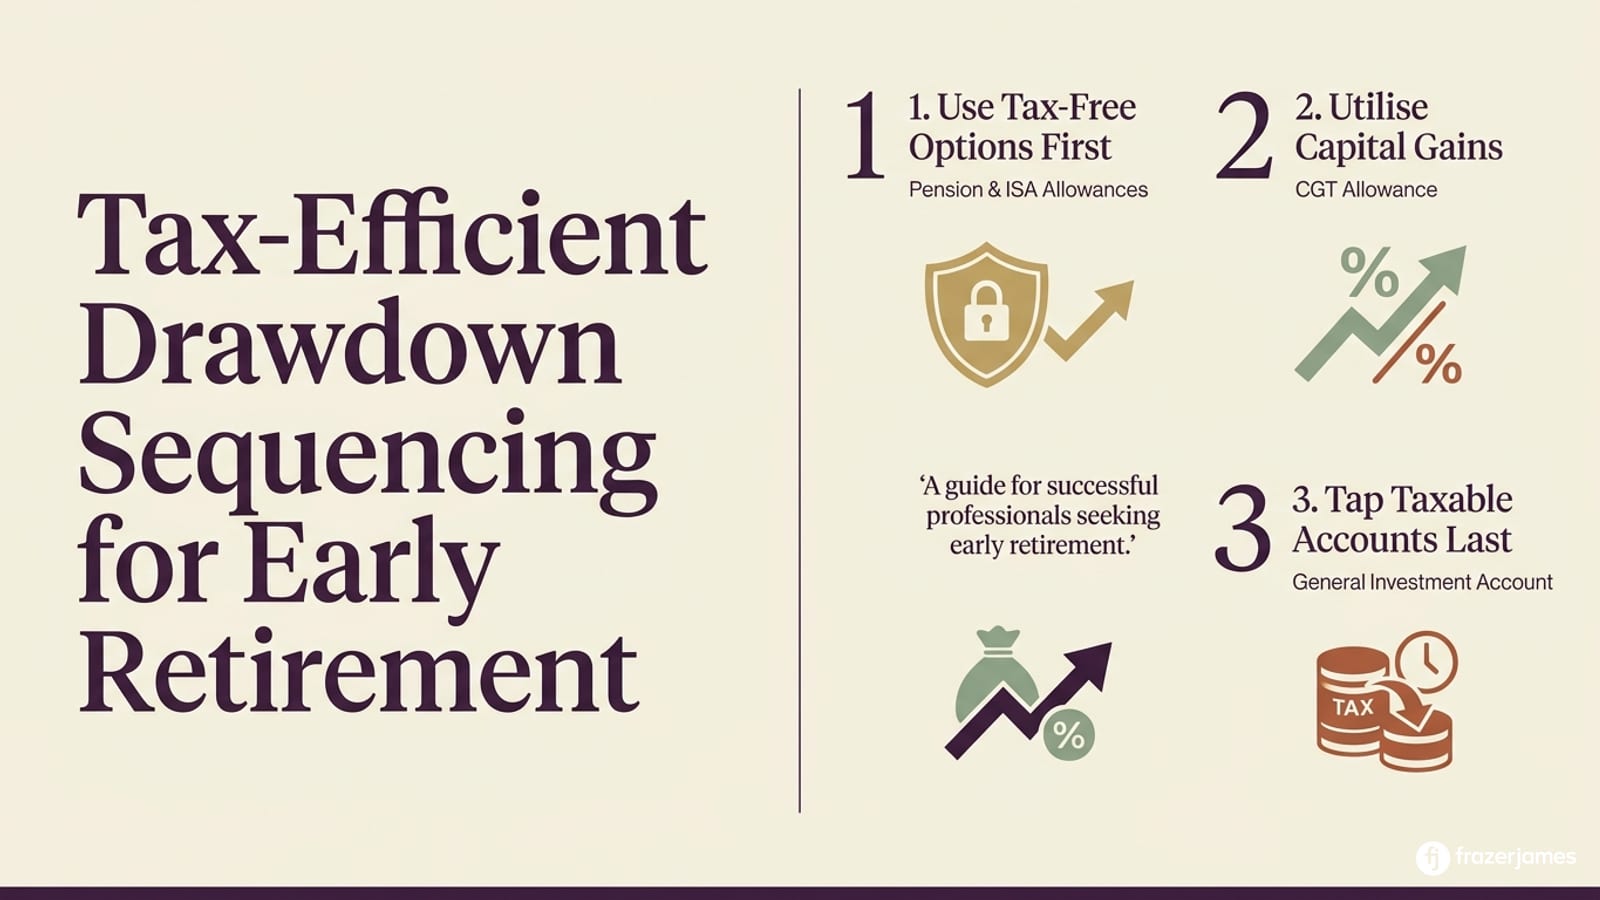
The core principle is this: you want to draw income in a way that keeps your total taxable income as low as possible in each tax year, while allowing your tax-sheltered assets to continue growing. In practice, this means thinking carefully about the order in which you access each pot.
A typical sequencing strategy for a professional retiring at 57 with a SIPP, ISAs, and a GIA might look like this. In the early years, draw primarily from ISAs (tax-free) and supplement with small SIPP withdrawals up to the personal allowance (currently £12,570 in 2026/27). This keeps taxable income low while allowing the remaining SIPP to grow. As the ISA is drawn down, increase SIPP withdrawals – but stay within the basic rate band (up to £50,270) where possible. When the State Pension begins at 66, it will consume part of the personal allowance, so the SIPP withdrawal strategy needs to adjust accordingly.
If you also have a GIA, capital gains can be realised each year up to the annual CGT exemption (currently £3,000 in 2026/27). Dividend income from a GIA is taxed at dividend rates, which are lower than income tax rates for higher earners – but still need to be factored into the overall picture.
The interaction between these sources is where the real planning value lies. A client who draws £50,000 per year entirely from their SIPP will pay significantly more tax than one who draws £20,000 from their SIPP, £20,000 from their ISA, and £10,000 from capital gains realisation – even though the total income is identical. Over a 20-year retirement, the difference can run to six figures.
One client, who works with us on his annual financial plan, described the value of this approach directly: “They are professional, proactive, and always looking for ways to add value through intelligent tax planning and smart investing. If you want to keep more of what you earn and stay on track, I can’t recommend them enough.”
For more on how we approach this with clients, see our page on long-term financial planning and how it integrates tax strategy with investment management.
What are the tax implications of retiring early in the UK?
Retiring early creates a specific tax challenge: you have multiple income sources with different tax treatments, and you need to manage them actively to avoid unnecessary tax. Pension drawdown is taxed as income. ISA withdrawals are tax-free. Capital gains from investments are taxed at CGT rates (currently 18% for basic rate taxpayers and 24% for higher rate taxpayers on most assets in 2026/27). Rental income is taxed at your marginal income tax rate. The State Pension, when it begins, is taxable income but is paid gross – meaning it reduces the headroom you have to draw from other taxable sources before hitting higher rate tax. Getting the sequencing right from day one of retirement, not just in the first year, is essential. The GOV.UK guidance on tax on pension income explains the basic rules, but the interaction between sources requires personalised modelling.
Business owners: how a planned exit can accelerate your path to early retirement
For business owners, early retirement often has an additional dimension: the business itself is a significant asset, and how you exit it determines how much wealth you actually crystallise. A poorly structured sale can result in a tax bill that materially reduces the proceeds available to fund retirement. A well-structured exit, planned years in advance, can be transformative.
Business Asset Disposal Relief (formerly Entrepreneurs’ Relief) allows qualifying business owners to pay Capital Gains Tax at 18% on the first £1 million of qualifying gains on a business sale, rather than the standard 24% higher rate. But the qualifying conditions – including the two-year ownership and trading company requirements – need to be met at the point of sale. Planning for this years in advance, not months, is what makes the difference.
One couple came to us with a successful business generating significant surplus cash but no clear strategy for managing it. They were concerned about inflation eroding the value of cash sitting in the business, and uncertain about how to transition from business wealth to personal financial security. By acting as their personal financial director, we helped them build a strategy that moved surplus profits into pension contributions (attracting corporation tax relief), built ISA wealth outside the business, and structured the eventual exit to minimise CGT. The result was a clear path to financial security that the business success alone had not provided.
If you’re a business owner thinking about your exit timeline, our page on financial planning for business owners considering an exit covers the key considerations in detail.
Can I retire early and still get my State Pension?
Yes. Stopping work early does not affect your entitlement to the State Pension – it simply means you wait longer to receive it. Your State Pension entitlement is based on your National Insurance record, and you need 35 qualifying years for the full new State Pension (currently £12,548 per year in 2026/27). If you retire early with fewer than 35 qualifying years, you can make voluntary Class 3 National Insurance contributions to fill gaps and protect your full entitlement. The cost of doing so is typically modest relative to the lifetime income gained. You can check your State Pension forecast and National Insurance record at GOV.UK’s State Pension age checker.
The lifestyle plan: what successful professionals need to retire TO, not just FROM
Here is the dimension that no financial guide addresses, and yet it is the one that determines whether early retirement actually works. For professionals who have spent 25 or 30 years building a career, identity and purpose are deeply tied to work. Retiring from something without a clear sense of what you are retiring to is one of the most common reasons early retirement fails – not financially, but personally.
We see this regularly. A client arrives with a clear financial plan and a target date. Six months into retirement, they are restless, disconnected, and quietly wondering whether they made the right decision. The financial plan was sound. The lifestyle plan was missing.
Mark and Pip had always hoped to retire early but were unsure whether they could make it happen – and equally unsure what they would do with the time. Working through both the financial and the lifestyle dimensions together, they moved past doubt and into a retirement filled with travel and new experiences. The financial plan gave them permission. The lifestyle plan gave them direction.
The practical implication for planning is this: your income target should be built around the life you actually want, not a generic estimate of “retirement spending.” If you want to travel extensively in the first decade of retirement, your spending in those years will be higher than in later years. If you plan to pursue expensive hobbies, that needs to be in the model. A retirement plan that doesn’t reflect your actual intentions is not a plan – it’s a spreadsheet.
For financial planning for successful professionals, the lifestyle dimension is as important as the numbers. We build both into every plan we create.
How a Chartered Financial Planner helps you model early retirement with clarity and confidence
The difference between a generic retirement calculator and a proper financial plan is the difference between a weather forecast and a navigation system. A calculator tells you roughly where you might end up. A plan tells you exactly how to get there, what to do when conditions change, and how to avoid the specific hazards on your route.
At frazerjames.co.uk, our Chartered and Certified Financial Planners use detailed cashflow forecasting to model your early retirement across multiple scenarios: different retirement ages, different market return assumptions, different spending levels, and different sequencing strategies. The model shows you not just whether you can retire early, but when, on what income, and with what level of confidence.
R S Lowe, a client planning for retirement, described the experience this way: “Rather than simply giving advice, they’ve taken the time to understand my circumstances and provide thoughtful, bespoke guidance. As I plan for retirement, it’s reassuring to know I have a team of knowledgeable experts supporting me every step of the way.”
One client, who came to us ahead of her own retirement, put it simply: “Their assessment, recommendations and advice has given me peace of mind about my financial future and the changes we’ve made to my pension pot investments have given excellent results.”
The value of working with a Chartered Financial Planner is not just the plan itself – it is the ongoing relationship. Tax rules change. Markets move. Life changes. A plan that was optimal in year one may need adjusting in year three. Having someone who understands your full picture, proactively reviews your position, and acts when action is needed is what turns a good plan into a genuinely secure retirement.
If you’re ready to understand exactly what early retirement could look like for you, book a free consultation with a Chartered Financial Planner and we’ll show you what’s possible.
About The Author

Frequently Asked Questions
This section covers how early retirement affects your State Pension and National Insurance record, retiring without a large pension pot, and working out how much you actually need.
How does early retirement affect my National Insurance record and State Pension entitlement?

Is it possible to retire early in the UK without a large pension pot?
How much money do I need to retire early in the UK?
Related news












Get in touch
Schedule a free consultation with one of our financial advisers, or give us call.
0117 990 2602