 Client Login
 Retirement assessment
 Book a call
 0117 990 2602


Modified on: November 2026
RSUs: A tech employee’s guide to Restricted Stock Units
Quick answer: RSUs (Restricted Stock Units) are shares your employer promises to give you on a future date. In the UK, you are taxed when the shares actually become yours, not when they are first promised. At that point they count as income, so you pay income tax and National Insurance on what they are worth that day, just like salary. You only pay Capital Gains Tax later if you keep the shares and they go up in value before you sell. For most people, selling the shares as soon as you get them and spreading the money elsewhere is the safer choice. And if your pay tips over £100,000 in a year, paying into a pension before 5 April can stop a hidden 60% tax rate from biting.
Earning £60,000 or more? Our guide to financial planning for high earners covers the 60% trap, Child Benefit and the pension taper.
What are Restricted Stock Units (RSUs)?
Restricted stock units (RSUs) are a form of employee equity compensation. It is a promise from your employer that you will be given shares in the company in the future. RSUs are a popular form of compensation at large technology companies, including Meta, Microsoft, Amazon, Intel and Google.
Over time, RSUs can become a significant part of your overall income and net worth. So, it’s critical to understand how they work, how they are taxed and have a strategy for managing them.
How do RSUs work?
RSUs are awarded to employees at critical events. Many large technology companies provide new employees with RSUs when they join the company. They may also be awarded annually or depending on company performance. RSUs share some similar characteristics with Company Share Schemes.
With RSUs, there are two key dates to remember: the grant date and the vesting date. The grant date is when the RSUs are awarded. The vest date is when the RSUs becomes available and can be sold. Typically, RSUs vest in tranches rather than all at once.
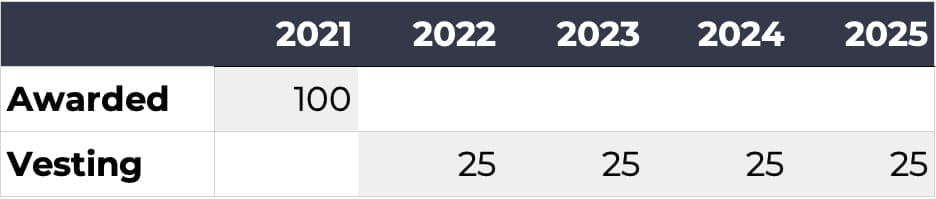
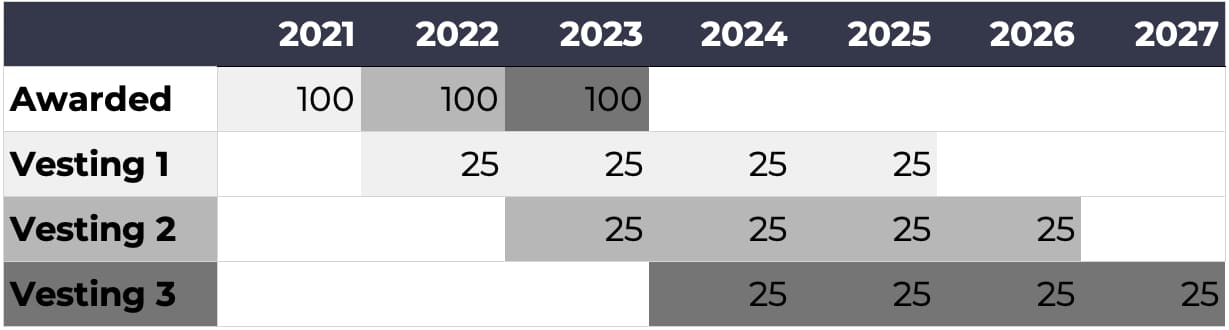
For example, assume that you start working at Microsoft in January 2021. You are provided 100 restricted stock units with a four-year vesting period when you join the company. Each year, 25% of the RSUs are vested. You are awarded an additional 100 restricted stock units every year after that.
In this example, 25 shares will vest after one year, 25 after the second year and so on.
For each additional year you work for the company, you are awarded 100 restricted stock units. This creates a ‘vesting cliff’, meaning a year contains multiple vesting periods.
How are RSUs taxed?
If you’re looking for an RSU tax calculator for the UK, ours is at the end of this section. It works out the tax when your RSUs vest, using 2026/27 rates. No calculator can capture everything, though. The exact tax treatment will depend on your financial circumstances, how your employer has set up the RSUs, and the vesting schedule.
In all cases, there is no tax to pay when RSUs are granted. You only pay tax on RSUs when they vest. The UK tax treatment for RSUs is similar to how your salary is taxed. When your RSUs vest, you will pay income tax and employee national insurance.
You may also need to pay for employers’ national insurance. Employers can pay this themselves or transfer the liability to you. You will need to check with your employer to understand how they approach employers national insurance.
If you are liable for employer national insurance, you must deduct this from the RSU vest value when working out your income tax. Confusingly, you don’t deduct the employer’s national insurance when working out your employee’s national insurance.
The below example calculates the tax you will pay when your RSUs vest. It assumes that you earn a salary of £150,000, receive RSUs of £50,000 and are liable for paying employers’ national insurance.
It shows that after paying all taxes, you will be left with just £22,375 from RSUs worth £50,000.
| RSUs received | |
|---|---|
| RSU value at vesting | £50,000 |
| Less employer NIC (15%)* | −£7,500 |
| Less income tax (45%, after employer NIC) | −£19,125 |
| Less employee NIC (2%)* | −£1,000 |
| RSU value after all taxes | £22,375 |
| Tax rate paid | 55.25% |
In most circumstances, the tax will be paid before you receive the shares (i.e. you will receive the net amount after withholding taxes). This is known as ‘sell to cover’, meaning shares are sold to cover the tax due. An alternative is that you pay the tax from your own cash savings and keep all the shares.
* Income tax/national insurance rates correct as of tax year 2026/27.
Use the calculator below for your own figures, or open the RSU tax calculator on its own page. The results are illustrative, not advice.
RSU Tax Calculator 2026/27
What will you keep from your RSUs when they vest?
RSUs are taxed as earnings on the day they vest, on top of your salary. Enter your salary and the shares vesting to see the National Insurance, the income tax and the value left after tax.
Based on tax rates and allowances in England, 2026/27
What the numbers say
Enter your salary, the number of shares vesting and the share price to see the tax and what you keep.
,
,
Where the vesting value goes
,
,
Illustrative only, not financial advice. Based on tax rates and allowances in England for 2026/27. Personal allowance £12,570, reduced by £1 for every £2 of income over £100,000. Basic rate 20% to £50,270, higher rate 40% to £125,140, then 45%. Employee National Insurance 8% between £12,570 and £50,270 and 2% above, employer National Insurance 15%. National Insurance is worked out on an annual basis, which is exact for directors and a close approximation for most employees. RSUs are taxed as earnings on their market value at vesting. Where employer National Insurance is transferred to you, it is 15% of the full value. It is deductible for income tax but does not reduce the value liable to National Insurance. The High Income Child Benefit Charge is 1% of the benefit for every £200 of adjusted net income over £60,000, the whole benefit at £80,000. Growth after vesting is a capital gain, not earnings. Scottish income tax bands differ. The results depend entirely on what you enter and your circumstances may differ. Talk your figures through with us, the first conversation is free.
How can I reduce tax on RSUs?
One way to reduce how much tax you pay on RSUs is by making pension contributions. This is because paying into a pension reduces your ‘adjusted net income’, reducing your tax bill and potentially your overall tax rate.
For example, assume you earn £100,000 and receive RSUs of £25,000. This gives you a total income of £125,000. Because the RSUs push your total income above £100,000, you will pay 60% income tax on the RSUs.
This is known as the 60% tax trap. For every £2 you earn above £100,000, your Allowance is reduced by £1. This means that in addition to paying the normal 40% tax, you also pay an additional 20% tax on income that was previously tax-free, resulting in a total tax rate of 60%
You can avoid paying this 60% tax charge by making a pension contribution. If you pay £25,000 into a pension, for tax purposes, you will have earned £75,000 and receive RSUs of £25,000. This gives you a total income of £100,000 and means you will avoid paying the 60% tax charge.
The below table shows that by paying £25,000 into a pension, you will save £4,250 in tax.
| RSUs received | £100k salary (no pension) | £100k salary (£25k pension) |
|---|---|---|
| RSU value | £25,000 | £25,000 |
| Less employer NIC (15%) | −£3,750 | −£3,750 |
| Less income tax (60% vs 40%, after employer NIC) | −£12,750 | −£8,500 |
| Less employee NIC (2%) | −£500 | −£500 |
| RSU value after all taxes | £8,000 | £12,250 |
| Tax rate paid | 68.00% | 51.00% |
Do I pay capital gains tax on RSUs?
Once RSUs vest, you can sell the shares immediately. There will be no additional taxes to pay if you do this. However, if you decide to hold onto the shares, you may pay capital gains on RSUs.
If the value of the shares increases between when they vest and when you sell them, you will have made a capital gain. Depending on how significant the gain is, you may need to pay capital gains tax.
Everyone has an annual capital gains tax allowance. For the 2026/27 tax year, the capital gains allowance is £3,000 per year. If the gain exceeds this, you will pay capital gains tax at 24% if you’re a higher rate taxpayer (18% for basic rate taxpayers).
Side note: despite the increase in capital gains tax rates in October 2024, capital gains are still taxed very favourably under current legislation. The top rate for capital gains is 24%, compared to 45% for income (or 60% if caught in the tax trap).
How can I minimise capital gains tax on my RSUs?
There are two ways to minimise capital gains tax.
- Sell the shares immediately upon vesting. This ensures that there is no gain to tax. If you still want to hold the shares, you could buy them back in a stocks and shares ISA. This ensures that future growth is tax-free (although you may still pay withholding taxes, mainly if the shares are held in a US company). If you hold the shares within a SIPP, any future growth is tax-free, and no withholding tax will apply (assuming that your pension administrator has set it up correctly!).
- Transfer some of your RSUs to your spouse. This is particularly useful if you have accrued large gains on the shares since vesting. Thanks to the inter-spousal transfer exemption, there is no tax to pay when transferring shares to your spouse. Your spouse can then sell the shares using their capital gains tax allowance. This enables you to sell double the shares before capital gains tax becomes payable. Whether you can transfer shares to your spouse will depend on the rule imposed by your brokerage platform.
What should I do with my RSUs?
For most people, the smartest move is to sell their RSUs as soon as they vest. Holding onto them not only exposes you to unnecessary risk but also creates a future capital gains tax bill that could eat into your profits.
More importantly, keeping RSUs means doubling down on your employer. You already rely on your company for your salary, bonuses, and career growth. Do you really want your investments tied up there too? While this strategy might pay off in a bull market, it can be disastrous when things turn south (just ask employees at Coinbase or Peloton).
A simple thought experiment: If your employer gave you a cash bonus, would you immediately reinvest it in company shares? If not, that’s a strong signal that selling your RSUs and diversifying is the better option.
How can we help?
RSUs are a valuable part of your financial picture, but they’re just one piece of the puzzle. At Frazer James, we specialise in helping tech professionals make smarter financial decisions, whether it’s managing RSUs, reducing tax liabilities, or ensuring your investments work harder for you.
Our expert financial planning goes beyond just RSUs. We help you integrate them into a broader strategy that includes tax efficiency, investment management, and retirement planning, so you can build real, lasting wealth.
If you want to make the most of your RSUs while securing your financial future, let’s talk. Book a consultation, and take the first step toward a smarter, more strategic approach to your finances.
Other clients we have helped
Financial Advisor Bristol and Pension Advisor Clifton
Frazer James Financial Advisers is an Independent Financial Advisor in Bristol, Clifton. About us: Frazer James Financial Advisers is a financial adviser in Bristol. We can provide independent and unbiased financial advice as an independent financial adviser. We provide independent financial advice, pension advice, investment advice, inheritance tax planning and insurance advice. If you want to speak to a Financial Advisor, we offer an Initial Financial Consultation without cost or commitment. Meetings are held either at our offices, by video or by telephone. Our telephone number is 0117 990 2602. Frazer James Financial Advisers is located at Square Works, 17–18 Berkeley Square, Bristol, BS8 1HB.
This article provides information about investing but not personal advice. If you are not sure which investments are suitable for you, please request advice. Remember that investments can go up and down in value; you may get back less than you put in.
This article provides general information about RSUs and UK taxation and does not constitute personal financial advice. Tax treatment depends on individual circumstances and may change. All rates shown are for the 2026/27 tax year and sourced from GOV.UK. Frazer James Limited is authorised and regulated by the Financial Conduct Authority (FCA no. 834451). You can verify this on the FCA register.
About The Author

Frequently Asked Questions
1. When are RSUs taxed in the UK?

2. Do I pay National Insurance on RSUs?
3. How is Capital Gains Tax calculated on RSUs?
4. What is the 60% tax trap on RSUs?
5. Can I transfer RSUs to my spouse to reduce tax?
6. What is a bed-and-ISA for RSUs?
7. Do I need to file a self-assessment return for RSUs?
8. What is Form W-8BEN and do I need it?
9. What happens to RSUs if I leave my employer?
10. How can Frazer James help me manage my RSUs?
Related news


Get in touch
Schedule a free consultation with one of our financial advisers, or give us call.
0117 990 2602