 Client Login
 Retirement assessment
 Book a call
 0117 990 2602


Modified on: September 2026
How much do I need to retire at 60? Your retirement guide.
How Much Do I Need to Retire at 60? Your Retirement Guide
A “good” pension pot at 60 isn’t a fixed number; it’s one that funds the retirement you actually want. The average UK private pension pot for individuals approaching retirement (aged 55–64) is approximately £137,800, which can generate a sustained retirement income when combined with the full State Pension of £241.30 per week (Source, GOV.UK, Analysis of Future Pension Incomes 2025 ) .
“The clients who are most anxious about retirement aren’t usually the ones with the smallest pots, they’re the ones who’ve never actually done the maths. Once we model their specific income, spending and timeline, the picture is almost always clearer than they expected. Sometimes better, occasionally worse, but always clearer.”
– James Mackay, Chartered Financial Planner and Managing Director at Frazer James IFA
Instead of asking “what’s the average?”, the more useful questions are:
- How much do you want to spend each year in retirement?
- What other income will you have (State Pension, final salary, rental)?
- How long do you need your money to last?
A good pension pot covers your lifestyle
A good pension pot isn’t just a number; it’s one that funds the life you want. Here’s what you need to consider:
- Your essential expenses (housing, food, bills).
- Your lifestyle spending (travel, hobbies, dining out).
- Your income sources (State Pension, final salary pensions, investments).
- One-off capital expenses (house repairs, car replacements, gifts for children).
Not sure what your number is? Our free retirement assessment gives you a personalised figure in under 30 minutes.
How much money do you need to retire at 60?
A widely used starting point is to have 20-25 times your annual retirement expenses saved. If your annual spending is £40,000, that suggests a target of £800,000- £1,000,000 across pensions, savings and investments.
| £800k
Minimum (20x £40k/yr) |
£1m
Target (25x £40k/yr) |
4% Safe withdrawal rate |
But this is where most guides stop, and where the really useful planning begins. Most retirees receive additional income, significantly reducing how much they need to draw from savings.
For example: your spending is £40,000 a year. You receive £12,548 from the State Pension (from age 67). You also get £4,000 from a final salary pension. You only need to draw £23,452 a year from your own savings. That changes your target pot considerably.
The key is building a plan around your income sources, not a generic multiple. Before calculating your number, check your State Pension forecast on GOV.UK.
How much income do you need to retire?
For most UK couples in 2026, a comfortable retirement costs between £43,100 and £60,600 per year. For a single person, a moderate retirement costs around £31,300 a year. These figures come from the Retirement Living Standards published by the PLSA, the most widely used benchmark for UK retirement income planning.
However, these figures are just benchmarks; your actual retirement costs will vary.
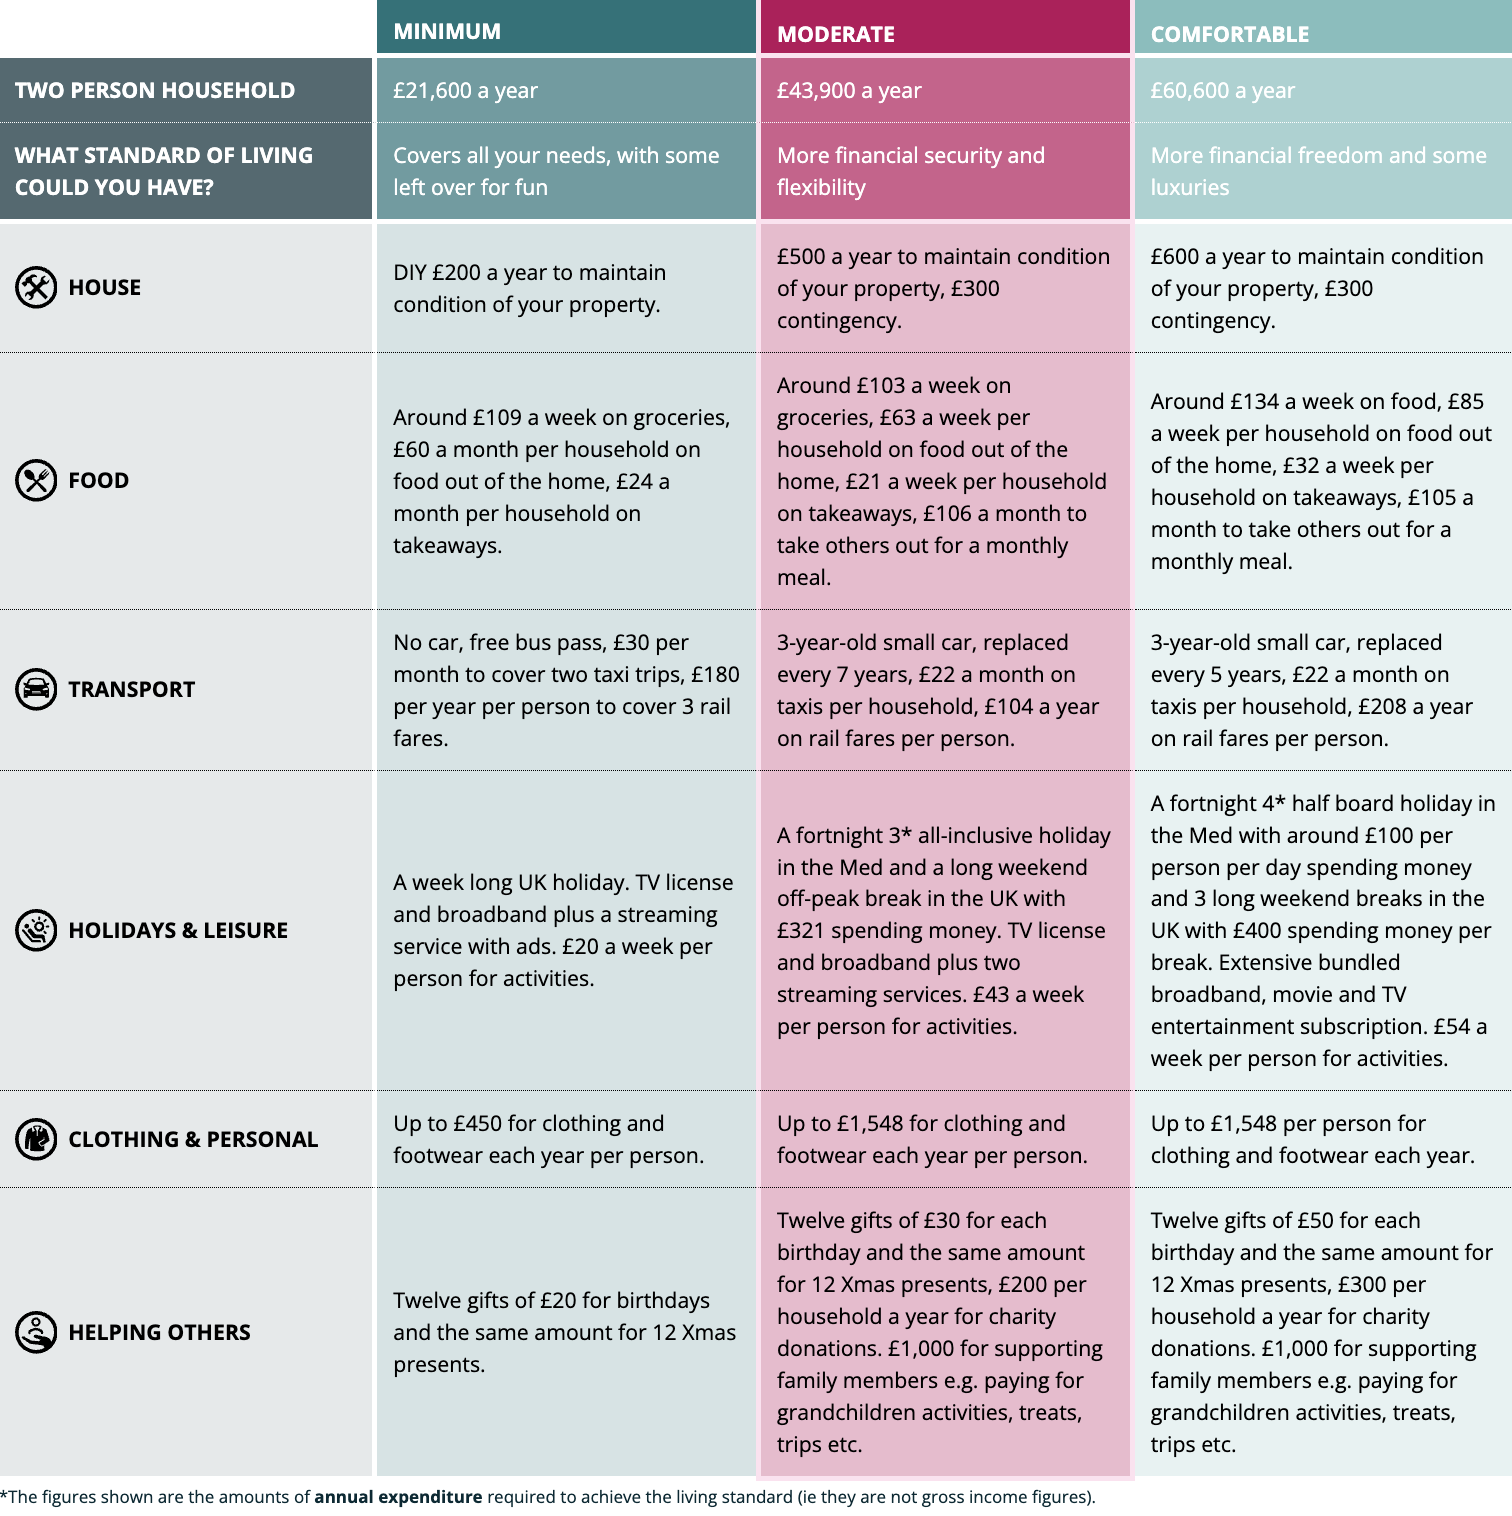
These benchmarks are a useful starting point. But your actual costs will depend on:
- Whether you own your home outright
- How much you travel
- What healthcare costs you expect
- Whether you’re planning to support family financially
Your personal retirement costs
The most reliable way to estimate your retirement spending is to start from what you spend now. If your monthly take-home is £5,000 and you save £1,500, you’re living on £3,500 a month, or £42,000 a year. That’s your baseline.
Then consider how that changes in retirement. Travel and leisure often increase in the early years. Commuting costs disappear. Mortgage payments may be gone. Healthcare costs tend to rise later. It’s not a single number; it changes across the decades.
To map this out properly, you can download our free retirement expenses worksheet.
Where will your retirement income come from?
Your income in retirement typically comes from two sources: regular monthly income streams and capital you draw down from savings and investments over time.
Regular income streams
This is the money that arrives in your bank account every month, similar to a salary. It may include:
- State Pension: State Pension: As of 6th April 2026, £12,547 a year for the full new State Pension. It starts at 67 for most people. If you retire at 60, you’ll have a 7-year gap to bridge. Check your forecast at GOV.UK.
- Final salary (defined benefit) pensions: Guaranteed income, but may not be accessible until 65 or later. Understand your scheme rules before making retirement plans.
- Savings interest and dividends: Income generated from investments, bonds or savings accounts.
- Rental income: If you own property, this can form a meaningful part of your income.
Drawing from your capital
This is money you draw down from your pension, ISAs and other savings over time. The most widely used framework is the 4% rule: withdrawing no more than 4% of your portfolio per year gives your savings a strong chance of lasting 30+ years.
On an £800,000 portfolio, 4% is £32,000 a year. Add in a State Pension of £12,547 and a final salary pension of £6,000, and your total income is £50,547, before you’ve touched the bulk of your capital. The exact figure depends on your State Pension entitlement.
“The 7-year gap between retiring at 60 and State Pension age at 67 is the piece most people don’t plan for in enough detail. If you retire at 60, you need to fund those first seven years almost entirely from your own savings. Get that bit right and the rest of the plan tends to hold together.”
– – James Mackay, Chartered Financial Planner and Managing Director at Frazer James IFA
How to create a retirement income plan
A retirement income plan maps out where your money comes from, when it starts, and whether it lasts. Here’s how to build one.
Step 1: Map out your income timeline
List every income source and when it starts. If you retire at 60, your State Pension won’t arrive until 67, that’s seven years of funding from savings alone. Final salary pensions may start at 65. Understanding this staggered timeline is the foundation of good retirement planning.
Step 2: Balance income and capital withdrawals
The goal is to spend the right amount at the right time without depleting your capital too early. The 4% rule is a useful ceiling, but in the early years of retirement, when you’re more active and spending more, many retirees draw a little more, then reduce withdrawals later.
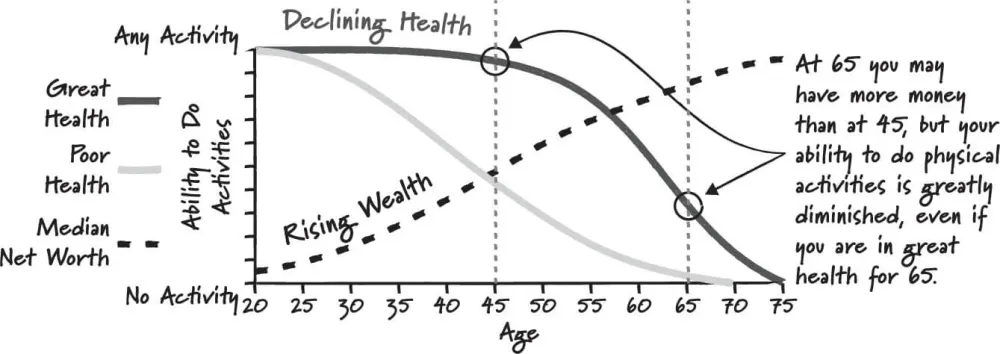
According to the book, Die with Zero by Bill Perkins, consider your time, health and money together. Money’s usefulness declines with age. Health matters most, no amount of money fixes poor health. Time only moves one way. The goal isn’t to die with the biggest number. It’s to maximise total life enjoyment. Sometimes that means spending earlier, not later. Balance abundant resources to get more scarce ones. Your money represents your life energy. Spend it on experiences. Those experiences are your return.
Step 3: Factor in tax and inflation
Two risks that are easy to underestimate are tax and inflation:
- Tax: Pension withdrawals above your personal allowance (currently £12,570 in May 2026) are subject to income tax. Structuring withdrawals across ISAs, pensions and General Investment Account can significantly reduce your bill.
- Inflation: Over time, £40,000 today won’t buy the same lifestyle in 20 years. Planning for inflation means adjusting withdrawals and ensuring investments continue growing.
This matters because without accounting for these factors, a plan that looks fine on paper can fail in practice. That’s why step 4 is essential.
Step 4: Use cash flow modelling
A retirement cash flow model shows, visually and numerically, whether your money is likely to last your lifetime. It accounts for tax, inflation, one-off expenditure, market fluctuations and different spending phases. This is what gives clients genuine confidence rather than educated guesswork. You can see a sample financial roadmap here.
Want to see your own cash flow model? We’ll build one for you in a complimentary 1-to-1 consultation.
What if you already have enough to retire at 60?
If the numbers stack up, the question isn’t financial, it’s personal. Too many people keep working simply because they haven’t done the maths, or because they’re worried about a risk that doesn’t really exist in their specific situation.
I recently worked with a couple who’d planned to retire at 65. After running their cash flow model, they realised they could have retired five years earlier and still have been financially secure. They’d been working those extra years unnecessarily. If you’ve built a solid financial foundation, the plan should make that clear, not leave you guessing.
What if you don’t have enough to retire at 60 yet?
Not being on track doesn’t mean retiring at 60 is off the table, it means a few adjustments may be needed. The most common levers are:
- Increase pension contributions: Even modest increases compound significantly over 5–10 years.
- Review your investment strategy: Many people are in funds that are too cautious for their timeline.
- Retiring a few years later: Two extra years of saving while not drawing down can make a meaningful difference.
- Reduce discretionary spending: Less in the years before retirement means a lower income target and a longer-lasting pot.
- Consider taking a final salary pension early: Sometimes worth it, but always check the reduction terms first.
How to retire at 60 without running out of money
The two main tools for creating a sustainable retirement income are annuities and pension drawdown. Most people benefit from understanding both, and many use a combination of the two.
1. Guaranteed income with an annuity
An annuity converts a lump sum into a guaranteed income for life. You’ll never run out, but the rates at 60 are low. A £200,000 annuity might generate around £4,848 a year at 60. That’s security, but not much spending power on its own (and you typically can’t leave remaining capital to beneficiaries).
2. Flexibility with pension drawdown
With drawdown, your pension remains invested, and you draw an income from it over time. This gives you flexibility and the potential for growth, but also means your pot can fall if markets perform poorly. Sticking to a sustainable withdrawal rate (around 4%) significantly reduces the risk of depleting your pot during your lifetime.
Which is better?
Neither, in isolation, is usually the right answer. The right strategy depends on your financial situation.
- If you need certainty and stability, an annuity provides guaranteed income.
- If you prefer flexibility and investment growth, drawdown gives you more control.
- Many retirees use a combination of both: securing a base income with an annuity and keeping extra funds invested.
Key Takeaways
- To retire at 60, most people need 20–25 times their annual spending, typically £500,000 to £1.5 million, depending on lifestyle.
- A comfortable retirement for a UK couple costs £43,100–£60,600 a year (PLSA 2026).
- The State Pension doesn’t start until 67, you need to bridge a 7-year gap from your own savings.
- The 4% withdrawal rule is a useful starting point, but your plan should account for tax, inflation and spending phases.
- Drawdown and annuities can be combined, you don’t have to choose one or the other.
- Many people can retire earlier than they think. The problem is usually not doing the maths, not the maths itself.
How can we help you retire at 60?
At Frazer James, we specialise in helping people retire with confidence. Whether you’re wondering if you have enough, looking for ways to maximise your retirement income, or need expert guidance on managing your pension, we’re here to help.
We’re an award-winning team of independent financial advisers, recognised as the Independent Financial Adviser of the Year for the South West. With a deep commitment to our clients, we’ve helped hundreds of people create financial security and retire earlier than they thought possible.
See How We’ve Helped Others Retire at 60
Still unsure if you’re ready? Watch this short video to hear directly from our clients who’ve worked with us. They share how we helped them gain clarity, retire comfortably, and take control of their financial future.
Book Your Free Retirement Consultation
Thinking about retiring at 60? A 1-2-1 consultation will help you:
✅ Assess your retirement readiness – find out if you can retire now or what adjustments you need.
✅ Understand your options – discover tax-efficient ways to maximise your retirement income.
✅ Get a clear plan – walk away with a personalised strategy tailored to your goals.
📅 Schedule your free retirement planning consultation and take the next step toward financial freedom.
Financial Advisor Bristol and Pension Advisor Clifton
This guide is for general information purposes only and does not constitute financial advice. The figures and examples shown are illustrative. Tax rules and pension legislation may change in the future. Your personal circumstances will affect your retirement planning outcomes.The Financial Conduct Authority does not regulate cash flow modelling, tax planning, or estate planning. The value of pensions and investments can go down as well as up. You may get back less than you invested. If you are unsure about your retirement planning, you should seek independent financial advice.
Frazer James Financial Advisers is an Independent Financial Advisor in Bristol, Clifton. About us: Frazer James Financial Advisers is a financial adviser in Bristol. As an independent financial adviser, we can provide independent and unbiased financial advice. We provide independent financial advice, pension advice, investment advice, inheritance tax planning and insurance advice. If you want to speak to a Financial Advisor, we offer an Initial Financial Consultation without cost or commitment. Meetings are held either at our offices, by video or by telephone. Our telephone number is 0117 990 2602. Frazer James Financial Advisers is located at Square Works, 17 – 18 Berkeley Square, Bristol, BS8 1HB. This article provides information about investing but not personal advice. If you’re not sure which investments are right for you, please request advice. Remember that investments can go up and down in value; you may get back less than you put in.
About The Author

Frequently Asked Questions
1. How much do I need to retire at 60 in the UK?

2. Can I access my pension at 60?
3. What is the best order to draw from my assets in retirement?
4. Will my pension be subject to inheritance tax?
Related news













Get in touch
Schedule a free consultation with one of our financial advisers, or give us call.
0117 990 2602