 Client Login
 Retirement assessment
 Book a call
 0117 990 2602


Modified on: October 2026
How much do I need to retire at 55 in the UK? A retirement planning guide.
How much do I need to retire at 55 in the UK? A retirement planning guide.
Quick answer: To retire at 55 in the UK, most people need somewhere between £750,000 and £1.5 million across pensions, savings and investments. Where you fall in that range depends almost entirely on how much you plan to spend each year and what other income you will have later. As a rough guide, a couple wanting a comfortable lifestyle needs around £60,600 a year (PLSA, 2025), and on the 25x rule that points to roughly £1.5 million before other income is counted. Someone with more modest spending, or a final salary pension and State Pension arriving later, may need considerably less of their own capital. One thing to plan around: the minimum pension access age rises from 55 to 57 on 6 April 2028. If you reach 55 before that date you can still access your pension; if you turn 55 after it, you will generally wait until 57 unless your scheme has a protected pension age.
This guide walks through how much you need, where the income will come from, and how to make a plan that ensures your money lasts a lifetime.
Close to retiring? Our retirement options guide takes you through each decision, with a short check to find your stage.
How much do I need to retire at 55?
Important: pension access age is changing. The normal minimum pension age is rising from 55 to 57 on 6 April 2028, confirmed by GOV.UK and legislated in the Finance Act 2022. If you were born before 6 April 1973, this change won’t affect when you can access your pension. If you were born on or after that date, build the later access age into your planning now, unless your scheme has a protected pension age (Source: House of Commons, Library briefing on minimum pension age).
Many people dream of retiring at 55, and it’s genuinely achievable with the right plan. Retiring at 55 gives you the freedom to travel, spend time with family, pursue interests you have always put off, and enjoy life while you are still in good health. The question is not really “can I retire at 55?”, it’s “how much do I need to retire at 55?”
To work out if you have enough to retire at age 55, there are a few questions you’ll need to answer. These are summarised below:
- How much will you spend each year?
- What income will you have and when?
- How long does the money need to last? (best guess at your life expectancy!)
If you retire at 55 and live to 90, that is 35 years of retirement, considerably longer than the 20 years most retirement calculators default to.
While you won’t know the exact answers to each of these questions, you can make an informed guess.
What is a good pension pot at 55?
Pensions are often the first thing people focus on when thinking about early retirement. So it comes as no surprise that one of the most common questions is: what is a good pension pot at 55?
The average UK pension pot at 55 is around £50,000 (Source: FCA Financial Lives Survey). That figure is almost universally unhelpful as a planning benchmark; it reflects the national average across all savers, including many who may not have prioritised pension saving. For early retirement, the number that matters is yours, not the average.
A good pension pot at 55 is one that, combined with all your other assets and income sources, supports the lifestyle you want for the rest of your life. That depends on how much you plan to spend, what other income you will have, and when that income starts.
“The clients who come to us most anxious about early retirement are usually the ones who have been comparing themselves to averages, or who have a number in their head from a conversation years ago. When we actually model their specific income, assets and spending, the picture is almost always clearer. Sometimes better than expected, occasionally more challenging, but always clearer.”
– Lewis Pollexfen, Chartered Financial Planner at Frazer James
How much money do you need to retire at 55?
A general starting point is to have saved around 25 times your expected annual expenses. Retiring at 55 is more demanding than retiring at 60 or 65, because your savings need to last longer. If your annual expenses are £30,000, a starting target is around £750,000 across pensions, savings and investments.
But the 25x rule is a starting point, not a final answer. Most people retiring at 55 will have income sources that reduce how much they need to draw from their own savings, such as the State Pension or a final salary pension from a previous employer. The question is not just how much you have, but how much you need to fund yourself until those other income streams begin.
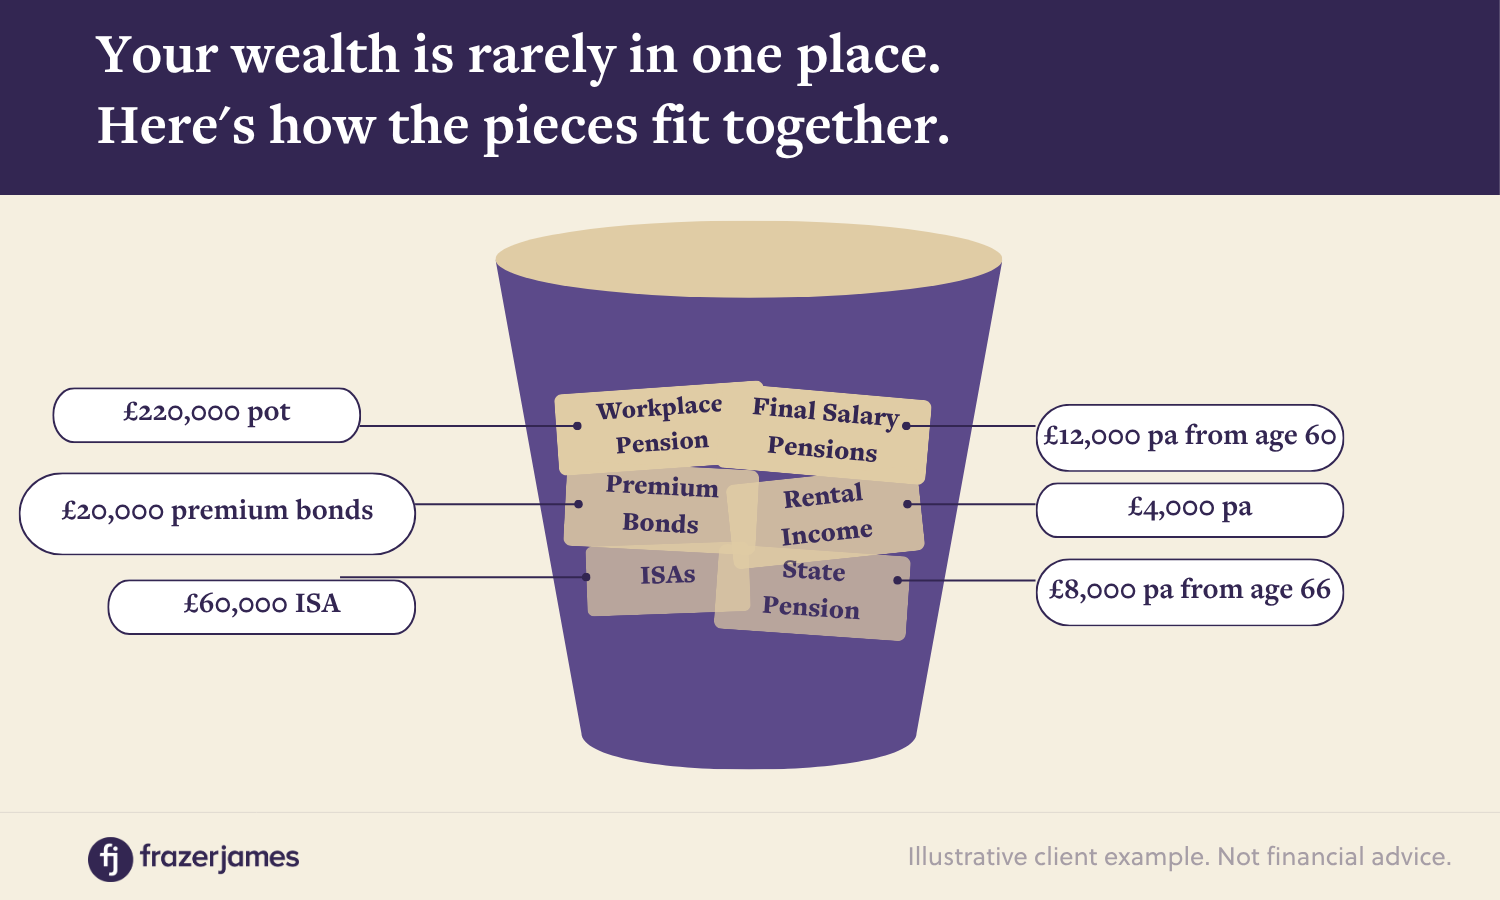
If you need £30,000 a year, but will later receive £12,548 (2026/27) from the State Pension (from age 67) and £4,000 from a final salary pension, you only need to fund £13,452 a year from your own savings once those benefits kick in. In the years before they start, you need to fund the full £30,000 yourself (Source: GOV.UK, Benefit & Pension Rates 2026-2027). This staged picture is where most retirement planning either comes together or falls apart.
How much income do you need to retire at 55?
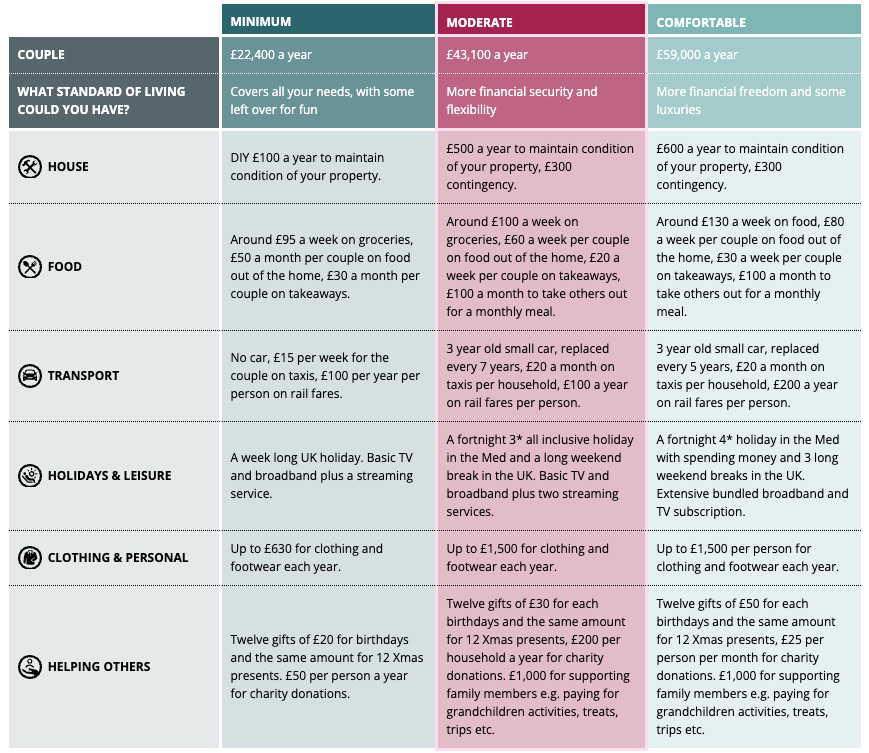
How much income you need depends on how much you plan to spend each year. The most widely used benchmarks in the UK come from the Retirement Living Standards, published by the Pensions and Lifetime Savings Association (PLSA) and calculated by the Centre for Research in Social Policy at Loughborough University. The 2025 figures are:
| Standard | One-person household | Two-person household |
| Minimum | £13,400/year | £21,600/year |
| Moderate | £31,700/year | £43,900/year |
| Comfortable | £43,900/year | £60,600/year |
Source: PLSA Retirement Living Standards 2025 update. Figures are after-tax income. Assumes no rent or mortgage costs.
These benchmarks are a useful anchor, but they are not your number. Your actual costs will depend on whether you own your home outright, how much you plan to travel, whether you have dependants, and what your health costs might be later in retirement. For someone retiring at 55, it is also worth thinking about spending in phases; most people spend more in active early retirement, then less in their 70s, then more again if care costs become relevant.
Estimating your personal retirement expenditure
The most reliable way to estimate your retirement spending is to start from what you spend now. If your take-home pay is £5,000 a month and you typically have £2,000 remaining after expenses, you are living on £3,000 a month. That is your baseline.
From there, consider what changes. Some costs disappear: commuting, work clothes, lunches out. Others increase: travel, leisure, and home maintenance. And some arrive later: healthcare, potentially care costs. A retirement timeline that maps different spending levels across different decades is far more useful than a single annual figure.
To help with this, we have created a retirement expenditure form you can download and complete.
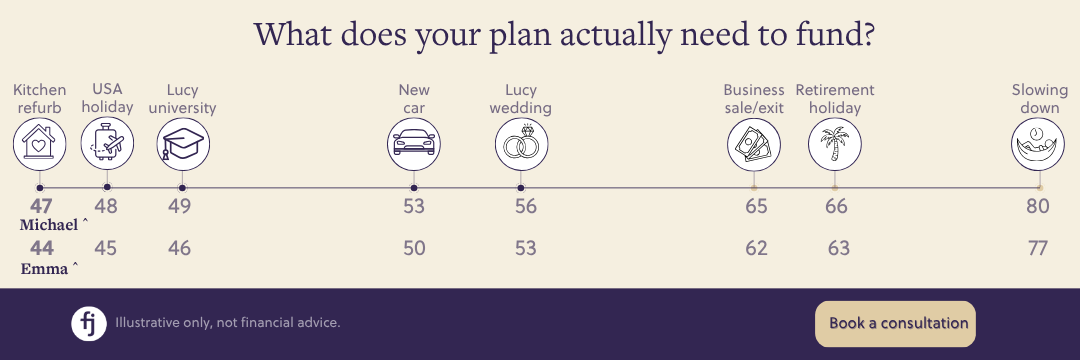
Creating a retirement timeline can be especially useful. This timeline should outline key events and expenditures throughout your retirement years, helping you better estimate your future costs.
How to fund your income when retiring at 55
Once you know how much you need to spend, the next step is mapping where the money will come from. In retirement, income typically comes from two sources: regular income that arrives consistently, and capital you draw down over time.
Regular income
Regular income includes savings interest, dividends from investments, rental income, and any final salary or defined benefit pensions. If you retire at 55, the State Pension will not be available until age 67 for most people, a 12-year gap to fund yourself. Depending on your final salary scheme, those payments may not begin until 60 or 65. Knowing exactly when each income stream starts is essential to understanding how much capital you need to bridge the gaps. You can check your State Pension forecast here. GOV.UK .
Capital
Capital is everything you have built up: pensions, ISAs, savings accounts, investment portfolios, and any property equity you plan to use. You will draw from this capital over time to supplement or replace income. A widely used guideline is to withdraw no more than 3% to 4% of your total capital each year, a rate that gives your portfolio a strong chance of lasting 30 or more years. For someone retiring at 55, a 35-year retirement is a realistic planning horizon, which makes the withdrawal rate discipline particularly important.
Balancing income and capital
The goal is to use income and capital in the right sequence. In the early years, before State Pension and final salary pensions kick in, you will typically draw more heavily from capital. Once regular income streams begin, drawdown from capital can be reduced. Mapping this sequence out over time, accounting for tax and inflation, is what a retirement income plan does.
Are you wondering if you have enough to retire at 55? Schedule a retirement review with us today to get personalised advice.
How to create a retirement income plan?
Once you have mapped your available funds and income sources, the equation is straightforward: income plus capital equals your retirement plan. The challenge is that a simple spreadsheet cannot do this well, as it does not account for tax, inflation, one-off expenditure, or the different spending phases across a 35-year retirement.
This is where cash flow modelling makes a material difference. A cash flow model integrates all your financial data, assets, income, spending, tax, and inflation, and produces a detailed forecast of how your money holds up over time. It answers the question that really matters: will it last?
The output is a personalised retirement report, a financial roadmap showing whether you are on track to retire at 55 comfortably, and what adjustments, if any, would strengthen your position. You can see a sample financial roadmap here.
What if you already have enough to retire at 55?
If the numbers stack up, the question stops being financial and becomes personal. Why wait? You have worked hard, saved deliberately, and managed your finances well. The plan should clearly tell you whether you are on track, and if so, give you the confidence to act on it.
I recently met a couple who had been working until 65, only for a cash flow analysis to show they could have retired a full decade earlier. The money was there, they just did not know it. That is the cost of not planning earlier.
Book a retirement review now to see if you’re ready to retire at 55.
What if you don’t have enough to retire at 55?
Not being on track does not mean retiring at 55 is out of reach. It means understanding which levers to pull and how much each one changes the outcome. The most common options are:
- Save a little more each year: Even modest increases compound significantly over time.
- Retire a few years later: Two or three extra years of saving while not drawing down makes a disproportionate difference to the total pot.
- Spend a little less in retirement: Reducing your annual spending target by even £250 per month can meaningfully change what is achievable.
- Review your investment strategy: Many people approaching retirement are in funds that are too cautious for their timeline.
A cash flow model can show you exactly how much each of these adjustments changes your retirement date and income. The goal is not to tell you what you cannot do, it’s to show you the specific steps that get you to where you want to be.
How can you retire at 55 without running out of money?
If you want to retire at 55 and ensure you never run out of money, purchasing an annuity is one way to achieve that. An annuity provides a guaranteed income for life, giving you peace of mind that your income will last as long as you do.
However, the downside is that annuities often offer lower income, meaning you’ll need a substantial pension to generate enough for a comfortable retirement.
Alternatively, you could opt for a flexible drawdown from your pension pot. This approach gives you control over how much you withdraw and when. But it comes with risks: withdraw too much, and you could exhaust your pension funds too quickly.
This is where the guidance of an independent financial adviser becomes invaluable. Regularly reviewing your pension with a professional can help ensure your funds last throughout your retirement.
Annuity vs drawdown
Since 2015, retirees can choose between purchasing an annuity or entering a flexible drawdown. But which option is best for you?
Annuity
An annuity converts a lump sum into a guaranteed income for life. You cannot run out, but the rates at 55 are low, because the provider is pricing in a potentially 35-year commitment. Annuity rates change constantly. For current indicative rates, the MoneyHelper annuity comparison tool is a good starting point. The security of an annuity makes it particularly well-suited to covering fixed essential costs.
Drawdown
Flexible drawdown keeps your pension invested while you withdraw from it over time. You control the amount and timing. The benefit is flexibility and continued growth potential; the risk is that withdrawing too much, or investing too cautiously, can exhaust the fund prematurely. Sticking to a sustainable withdrawal rate, typically 3% to 4% per year for someone retiring at 55, significantly reduces this risk.
Choosing the right option
The best option depends on your personal circumstances. A drawdown might work well if other income sources already cover your basic needs, giving you more flexibility for additional spending. However, an annuity could be the safer choice if you need guaranteed income to cover essentials. Many people find that a mix of both strategies works best.
As independent financial advisers, we can help you determine the ideal strategy based on your unique situation. Your drawdown can also be used to top up your income in small amounts while keeping most of your pension invested.
Need help deciding? Schedule a consultation with us to explore your retirement options.
How can we help you retire at 55?
At Frazer James, we are dedicated to helping you achieve your goal of retiring at 55 with confidence and financial security. As award-winning independent financial advisers and specialist retirement planners, we have the expertise and experience to guide you through the complexities of early retirement. Our recognition as the Independent Financial Adviser of the Year for the South West underscores our commitment to excellence.
We’ll work alongside you to thoroughly assess your financial situation and determine if you’re on track to retire at 55. Based on this assessment, we’ll develop a customised retirement plan that aligns with your goals and aspirations.
Curious about how we can help you? Watch our video to hear from clients who have partnered with Frazer James for their retirement planning. Discover how we’ve supported them in achieving their dream of early retirement with clarity and peace of mind.
Key Takeaways
- The normal minimum pension access age is rising from 55 to 57 on 6 April 2028. If your planned retirement date is after this, you will need to access income from ISAs, savings or other sources until you reach 57. Source: GOV.UK .
- Most people need around 25 times their annual expenses to retire at 55. On £30,000 a year spending, that is £750,000, before accounting for the State Pension and other income that arrives later.
- A comfortable retirement for a couple costs £60,600 a year (PLSA 2025). For a single person, a moderate retirement costs £31,700. Source: PLSA Retirement Living Standards 2025.
- Retiring at 55 means bridging at least 12 years before the State Pension (£12,548 a year for 2026/27) begins at 67. That gap needs to be funded from pensions, ISAs and other savings.
- A sustainable withdrawal rate for a 35-year retirement is typically 3% to 4% of your portfolio per year. Higher rates significantly increase the risk of running out of money.
- Annuities and drawdown are not mutually exclusive. Many people use annuities to secure a floor of essential income and drawdown for flexibility on top.
Schedule your retirement consultation.
If you’re considering retiring at 55 and want expert guidance, now is the time to take action.
During this 1-2-1 consultation, we’ll assess your retirement readiness, explore your options, and provide tailored advice to help you confidently achieve your early retirement goals. Don’t leave your future to chance. Get the professional advice you need to retire at 55 on your terms.
Schedule your retirement planning consultation.
Financial Advisor Bristol and Pension Advisor Clifton
Frazer James Financial Advisers is an Independent Financial Advisor in Bristol, Clifton. We provide independent financial advice, including pension advice, investment advice, inheritance tax planning and insurance advice. If you want to speak to a Financial Advisor, we offer an Initial Consultation without cost or commitment. Meetings are held either at our offices, by video or by telephone. Our telephone number is 0117 990 2602. Frazer James Financial Advisers is located at Square Works, 17 – 18 Berkeley Square, Bristol, BS8 1HB. This article provides information about investing but not personal advice. If you’re not sure which investments are suitable for you, please request advice. Remember that investments can go up and down in value; you may get back less than you put in.
About The Author

Frequently Asked Questions
Can I retire at 55 if I was born after April 1973?

How much tax-free cash can I take from my pension?
What happens to my State Pension if I retire at 55?
Is the 4% withdrawal rule safe for a 35-year retirement?
Related news


Get in touch
Schedule a free consultation with one of our financial advisers, or give us call.
0117 990 2602